USD/JPY into 18 September: the guidance gap, not the hike
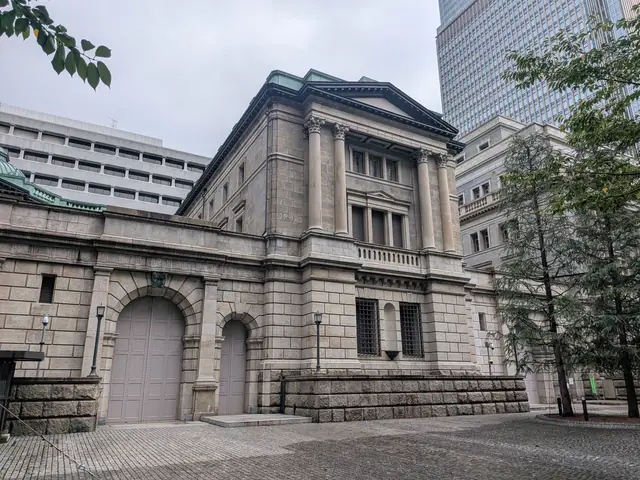
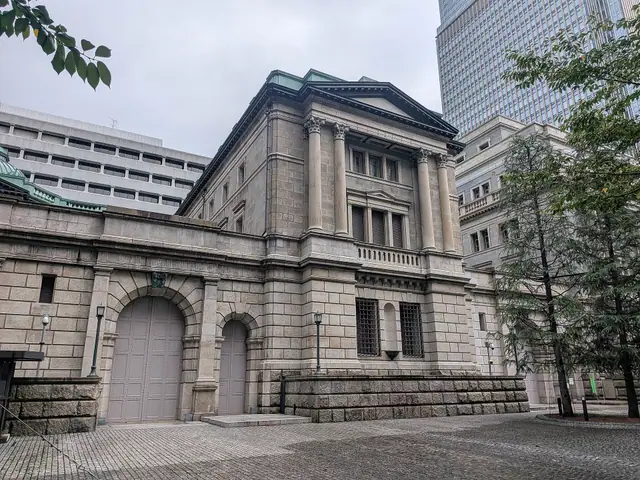
The Fed and the Bank of Japan are both expected to tighten within three days, so USD/JPY prices the guidance differential, not the decisions. Base case 152.00.
Desk
Market calls with a spot, a target and an invalidation level.
287 stories since 2018 · page 3 of 15
September 2026
The Fed and the Bank of Japan are both expected to tighten within three days, so USD/JPY prices the guidance differential, not the decisions. Base case 152.00.
EUR/PLN reaches 4.40 by November 4 in the base case as the NBP-ECB policy gap shrinks to 125bp. Key levels, catalysts and four signals that would break the call.
EUR/NOK to 11.00 by Norges Bank's November 5 decision: the ECB's September hike has thinned the krone's rate premium and Norges Bank's FX flows now sell krone.
USD/JPY at 153.27 fell 4% while the US-Japan 2-year spread held at 259.7bp. Why Takata's 1.25% dissent, not carry, sets the path to 150 by October 30.
The RBOB-Brent gasoline crack has priced September's grade switch but none of the Hormuz product shock. Base case $46/bbl by October 30; invalidation $33.70.
EUR/SEK fixed at 11.1620 on September 7, 2026, a 12-month high. But the Riksbank governor has pre-announced a rise: the gap-compression case for 11.05.
The US 30-year Treasury yield, at 5.24%, reaches 5.50% by the October 27-28 FOMC as an inverted 20s30s spread repairs into a Fed priced to tighten.
GBP/AUD trades at 1.8783 after a 100 basis point swing in the RBA-BoE policy gap. Base case 1.8400 by the November 3 RBA decision; 1.9200 invalidates.
USD/BRL to 5.45 by October 25, 2026: CME speculative long-real positioning sits at the 99th percentile as Copom goes dark for 49 days into the runoff.
Managed money added 191,573 net corn contracts in a fortnight, into the second-largest US crop on record. Why CZ26 targets 475 c/bu by the 14 December expiry.
Silver at $64.12, 8.7% below the August 28 LBMA fix. CFTC net length rose into the top and Warsh says the Fed has work to do. Base case $58 by September 30.
SOFR–IORB sits at 0bp against +22bp at the last year-end. The call: at or below +10bp on December 31, 2026, with the Standing Repo Facility as the ceiling.
August 2026
USD/TRY at 48.245 after the CBRT restarted one-week repo auctions on August 23, cutting effective funding 300bp. Base case 50.00 by October 31, 2026.
EU carbon allowances closed at €82.87/t. The Market Stability Reserve intake from September 1 draws the ETS surplus to exactly 833 million — and to €90/t.
US distillate stocks sit 9.5% below last year and exports run 28.5% higher, yet the EIA forecasts a Q4 build. The case for ULSD at $4.40 by year-end 2026.
USD/ZAR to 15.50 by year-end 2026: SARB 3% target keeps the repo at 7% as CPI falls to 4.3%, widening the real rate while gold tops $4,500 and DXY sits below 100.
France's 10-year OAT yields more than Italy's BTP despite a far stronger rating. The OAT–Bund spread widens from 85.7bp to 105bp by end-Q1 2027.
EUR/JPY is at 185.70 after fully retracing the joint US-Japan yen intervention. The euro-Japan policy spread has been frozen since December 2025.
The UK 10-year gilt yielded 5.0493% on August 25, 2026. Base case 5.35% by the October 28 Budget as fiscal supply risk and a rising CPI rebuild the premium.