Yen, Havens Extend Climb, Aussie Lags Amidst Trade Fears
Yen, Havens Extend Climb, Aussie Lags Amidst Trade Fears US Yields Drop, Dollar Modestly Lower, Stocks Settle Down

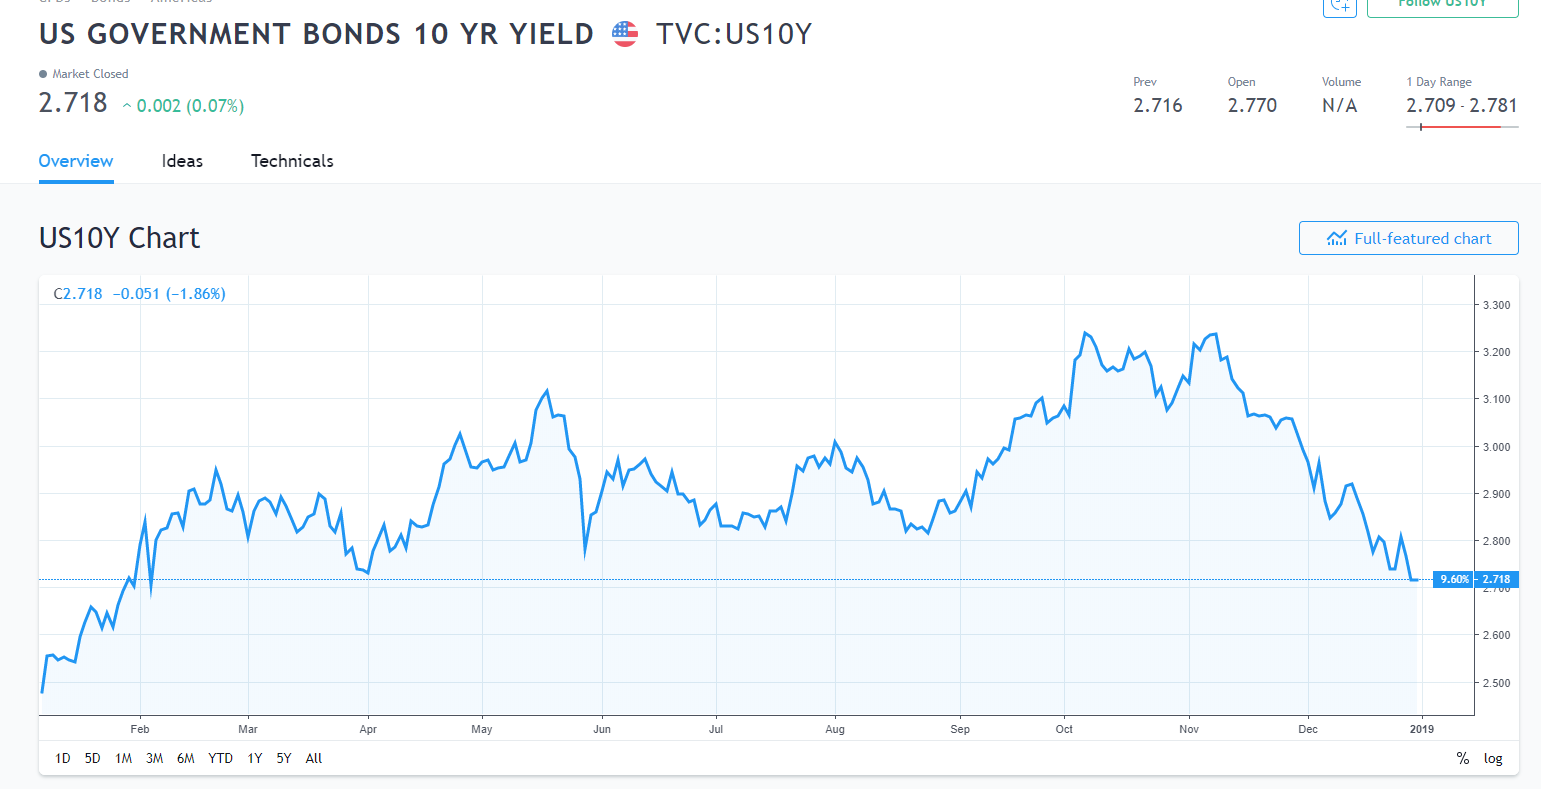
Summary: After another volatile session the Dollar and stocks settled to end mostly lower. The Yen and Swiss Franc led haven currencies higher while the Aussie and Risk currencies lagged. US Treasuries rallied as yields dropped. The benchmark US 10-year note fell to 2.72%, a level not seen since February. The Dollar Index (USD/DXY) slipped 0.20% to 96.37 (96.48 Friday).
Trading volumes remained low as China and Japan had their final trading day of 2018.
Wall Street stocks settled lower after a wild week. The S&P 500 ended 0.12% down.
- USD/JPY – The Japanese Yen extended its gains, finishing as top-performer against the fading US Dollar. USD/JPY dipped to 110.30, down 0.56% from Friday morning’s 110.67. The six-basis point drop in the US Ten-year yield to 2.72% weighed heavily on the Greenback.
- EUR/USD – The Single Currency finished little-changed against the Dollar, closing at 1.1442 (1.1446 Friday). EUR/USD traded to a high of 1.1473, within striking distance of strong resistance at 1.1500. Over the weekend, the Italian parliament approved a revised budget deficit to avoid sanctions from the European Commission, a Euro positive.
- AUD/USD – The Aussie managed a modest, albeit tentative recovery to 0.7038 from 0.7025 Friday morning. Continuing trade worries which have affected the global growth outlook and risk sentiment has seen the Aussie underperform its global peers.
- US 10-year bond yield – slumped 6 basis points to 10-month lows at 2.72%. Other global yields were little-changed. Which saw the Dollar Index (USD/DXY) slip lower. By contrast Germany’s 10-year Bund yield was up 2 basis points to 0.24%. The yield on Japan’s 10-year was flat at 0.01%.
On the Lookout: Volumes will remain low and the last trading day of 2018 will be a slow one. Japan and China are out today. The partial US government shut-down will only add to the uncertainty in the markets which will weigh on the already bruised risk sentiment.
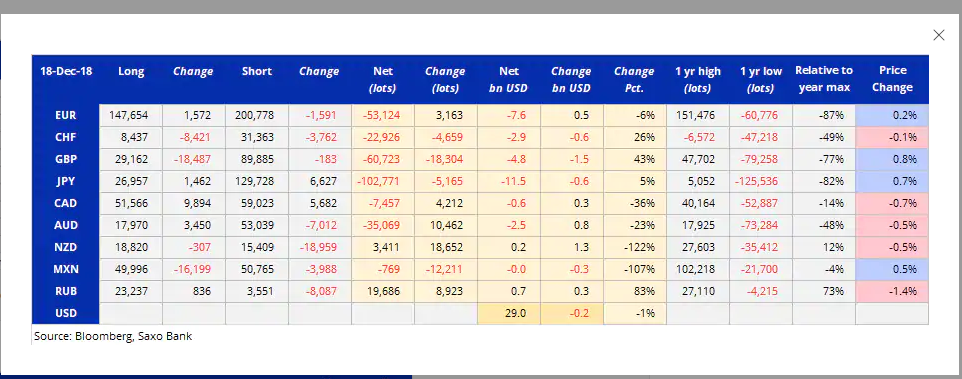
Meantime speculative market positioning remained long of Dollar bets heading into the last trading week of 2018. The latest CFTC report for the week ended December 18 saw Dollar longs against 7 out of the 9 currencies it records.
The New Year holidays will make for a limited economic calendar for the early part of this week. Today sees Chinese December Manufacturing and Non-Manufacturing data. The highlight of the week comes on Friday with US December Payrolls.
Trading Outlook: This week boils down to liquidity. The drop in US yields will continue to erode support for the US Dollar against its Rivals. Speculative market positioning, which is long USD bets will also add pressure to the Greenback. The US Dollar may just have seen its best days as we head into 2019.
- USD/JPY – With Tokyo out today, trading should be slow on the Japanese currency. However, this currency will continue to lead the Dollar lower. USD/JPY has immediate support at 110.10 (overnight low was 110.143). A sustained break of the 110.00 psychological level could see 109.50 very quickly. With US yields where they are, we could be headed back to the 108.00 area.
- EUR/USD – While the Euro was little-changed, the Single currency continues to grind higher. EUR/USD traded to a high of 1.1473 on Friday, with 1.1500 beckoning. European economic data has not been supportive of the currency as the latest Euro-area PMI and CPI data underperformed. However, an overall weaker US Dollar could see further Euro gains. The immediate resistance at 1.1500 remains a threat with 1.1550 possible.
- AUD/USD – The Aussie has been the worst performer among the G10 Major currencies in 2018. The Australian Dollar is the proxy for Chinese and global economic growth and is considered a risk barometer. It is the most liquid of the Risk and Asian currencies. The Aussie has also fallen against its major traded partners. The Aussie Trade Weighted Index fell to its 2018 low at 60.60 against a high of 65.70 in January. This is one barometer which the RBA monitors and a drop of this magnitude will see the RBA keep rates unchanged, not lower them. The yield differential between US and Australian 10-year bond yields has narrowed to 36 basis points from 48 in November. The latest CFTC report saw that while speculators trimmed their Aussie short bets. They are still short (-AUD 35,069 contracts). While it looks vulnerable near the 0.70 cent mark, a weaker overall US Dollar will provide the Aussie the needed support to grind its way higher.
- USD 10-Year Bond Yield – The 10-year bond slumped to a low of 2.70% before recovering to 2.72% at the close, down 6 basis points. Immediate support can be found at 2.70% and a clean break could see us headed to 2.60%. Rallies will be limited to overhead resistance at 2.80 and 2.85 %.
Wishing all a very Happy New Year. Happy trading ahead..
Reporting by Michael Moran. Filed 31 December 2018, 00:46 GMT.


