Oil, Risk Appetite Stabilise, Stocks Climb, Dollar Ends Mixed
Oil, Risk Appetite Stabilise, Stocks Climb, Dollar Ends Mixed Euro Underwhelms, Aussie Lifts, Yen Flat, Pound Mildly Up

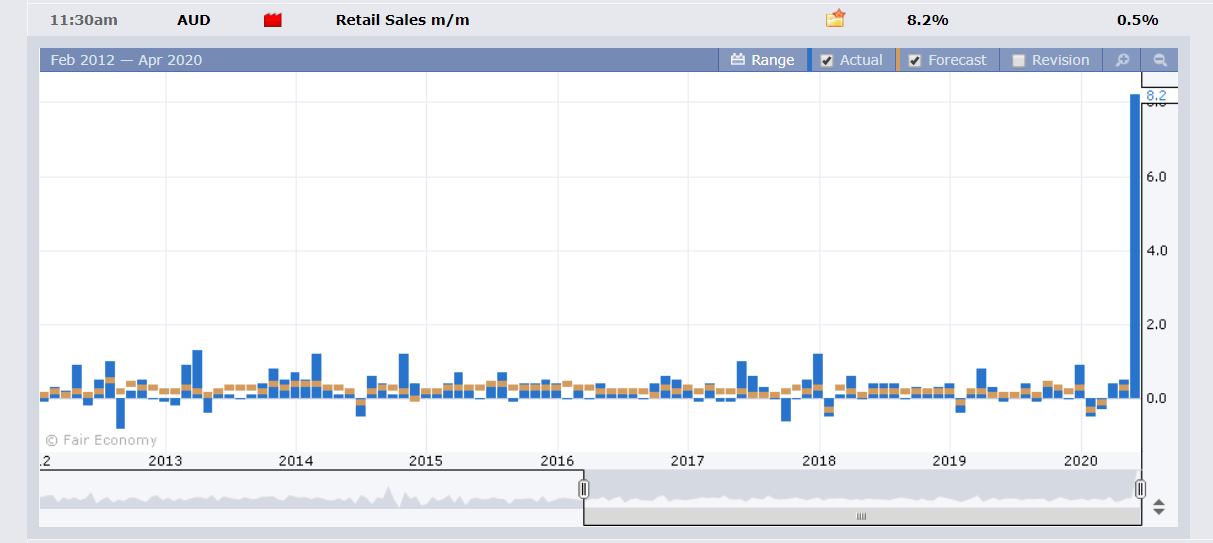
Summary: Risk appetite stabilised as oil prices recovered following two days of furious losses. Equities rebounded with the US House of Representatives set to pass a new coronavirus stimulus package worth around USD 500 billon. FX was cautious in muted trade. The Dollar finished mixed against its rivals with the Euro underwhelming, down 0.35% against the Greenback at 1.0822 (1.0859). European Union leaders meet today to try and come up with a plan to help economies recover from the coronavirus outbreak amid major disagreements. Sterling was up modestly to 1.2330 from 1.2300. The Australian Dollar finished as best performing currency, up 0.38% to 0.6322 (0.6286). Preliminary Australian Retail Sales in March (pre-lockdown) climbed 8.2% on a surge in hygiene products. Against the oil sensitive Canadian Loonie, the US Dollar eased to 1.4162 from 1.4200. The USD/JPY pair ended flat at 107.75. Asian and EM currencies halted 2 days of losses against the Greenback. USD/THB (US Dollar/Thai Baht) retreated t0 32.38 (32.52) while the Dollar fell 0.7% against the Indian Rupee to 76.45. Wall Street stocks closed higher. The DOW was up 2.2 % to 23,485 (23,035) while the S&P 500 added 2.3% to 2,801 (2,740). Bond yields climbed with the benchmark US 10-year rate up 4 basis points to 0.62%. Germany’s 10-year Bund yield ended at -0.41% from -0.48%.
Other data released yesterday saw UK Annual CPI in March match forecasts at 1.5%. Core PPI rose 1.6%, also matching expectations. Canada’s March CPI (monthly) fell to -0.6% from February’s +0.4%, missing forecasts at -0.4%. Eurozone March Consumer Confidence fell to -23.0 from -12 in February, underwhelming forecasts at -20.0.
On the Lookout: The data front picks up today with global Manufacturing and Services PMI’s. Australia kicks off with its Commonwealth Bank Preliminary Manufacturing and Services PMI’s for April. March’s PMI data were both revised lower. Australia’s Trade Balance (March) will also be released. Japanese Flash Manufacturing PMI’s and Leading Economic Indicators follow. New Zealand reports on its Annual Credit Card Spending for March. European reports start off with the Eurozone GFK Consumer Climate followed by UK Public Sector Net Borrowing. French, German and Eurozone Flash Manufacturing and Services PMI’s follow. The UK reports its Flash Manufacturing and Services PMI’s and CBI Industrial Trends Survey. The US Initial Weekly Unemployment Claims, Flash Manufacturing and Services PMI’s round up the day’s reports.
Markets will look carefully into the data. The US Initial Jobless Claims will take the limelight with a smaller loss forecast at 4.35 million from the previous 5.245 million. Amidst all of this, the US economy inches closer to a re-opening.
Expectations are for a deterioration in the overall data as the world economy faces a contraction by -2% in 2020. It becomes a battle with the relief packages and the gradual opening from lockdowns of different countries.
Trading Perspective: The Dollar Index, (USD/DXY) saw a modest rise to 100.353 from 100.207 mainly due to the 0.38% fall in the Euro (which takes almost 60% of the weight in the USD/DXY). Commodity currencies, the Aussie, Loonie and Kiwi all advanced after oil prices stabilised and the CRB Index rebounded. Against the Yen, the US Dollar was flat. All this is saying is that we can expect consolidation at current levels with the Euro looking particularly vulnerable. Equity gains were modest. Expect further consolidation with volatility just around the corner.
AUD/USD – Recovers to End Above 0.6300; 0.6400/50 Resists
The Australian Dollar recovered from strong selling interest which pushed the Battler to an overnight low at 0.62762. AUD/USD rallied to finish in late New York at 0.6322. Overnight high traded was 0.63527. The Australian Bureau of Statistics released a Preliminary March Retail Sales report that saw a strong rise of 8.2% as the country prepares to gradually re-open its economy. Australia has been one of the few countries to be able to control the coronavirus outbreak as PM Scott Morrison closed its borders before the WHO declared a global pandemic. The rise though in the Retail Sales was due to a surge in hygiene products and dried foods prior to the lockdown. Which makes it more of a one-off. More economic data ahead will show the real impact and damage.
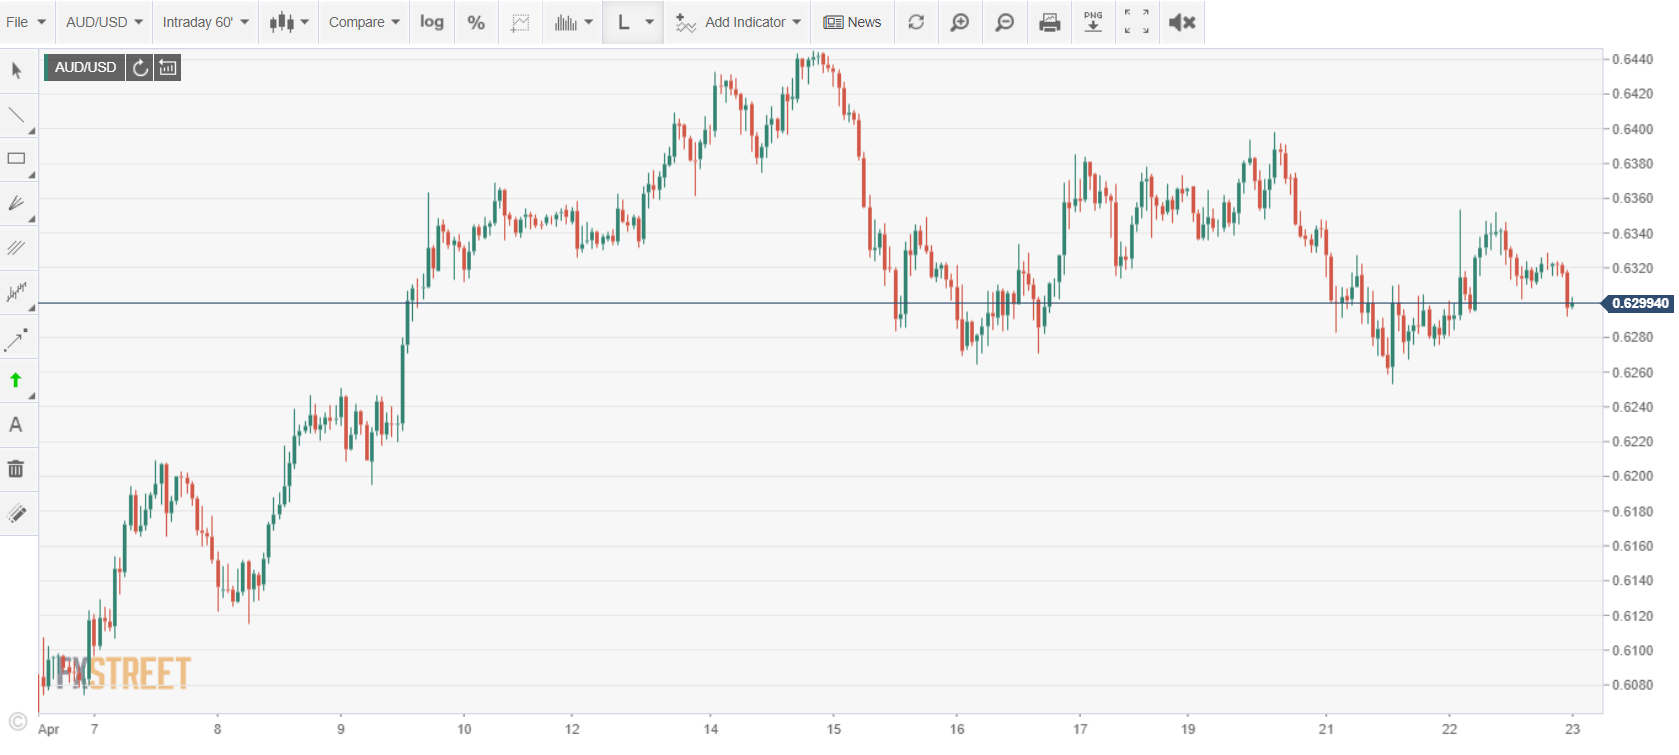
AUD/USD has immediate resistance at 0.6360 followed by 0.6400. Strong resistance remains at 0.6450. Immediate support lies at 0.6275 followed by 0.6245. Look for a choppy trading within a 0.6285-0.6385 range today. Just trade the range on this one, too early to tell which way the US Dollar is headed.
EUR/USD – Edging Lower, Euro Council Meet Crucial, 1.0780-1.09 For Now
The Euro finished as worst performing major currency, down 0.35% at the New York close to 1.0822, not far off its overnight and two-week low at 1.08033. EUR/USD opened yesterday at 1.0860. The shared currency has fallen in the last 5 trading days. FX was mostly muted yesterday with the focus on oil and asset markets. Today the currencies heat up with the release of Global Manufacturing and Services PMI’s. Euro area and Eurozone PMI’s are forecast to be lower, and if they come out better than forecast, it could provide a reprieve for the Euro. Any rebound looks to be limited. The big event is tomorrow’s European Council meeting amidst a lack of progress in talks leading into the event.
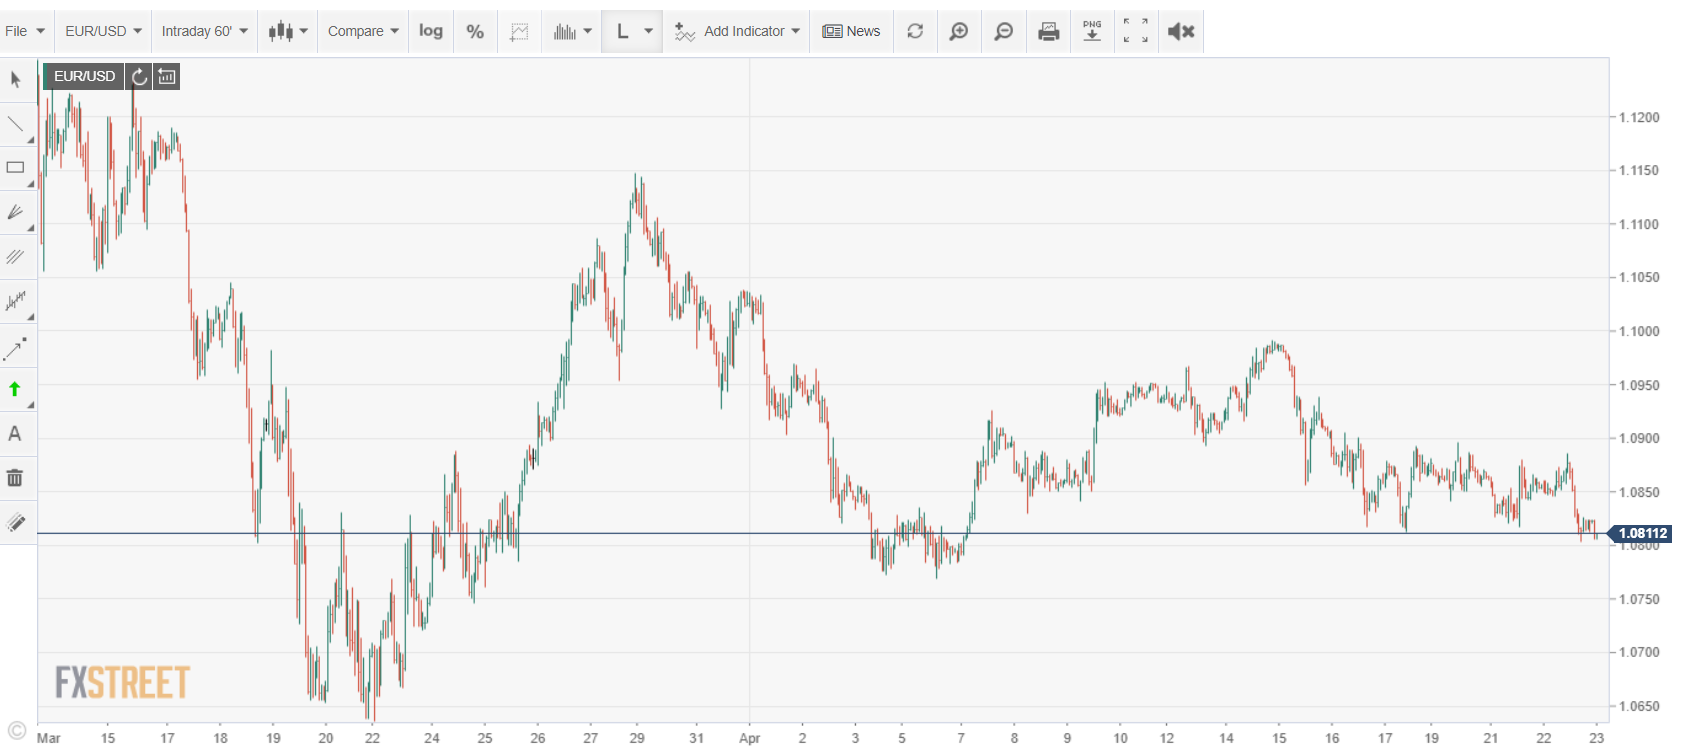
EUR/USD has immediate support at 1.0800 followed by 1.0750. Immediate resistance can be found at 1.0880 (overnight high 1.0885) and 1.0900. We highlighted this week that net speculative Euro long bets increased to the biggest levels not seen since 2018. Just as a reminder, net speculative Euro long bets rose to +EUR 86,617 contracts, up almost +EUR 7,000 contracts from the previous week. As the robot in the old TV series “Lost In Space” used to say to Will Smith.. “danger, danger..”
Look to sell rallies in a likely range today of 1.0785-1.0885.
USD/JPY – Grinding Up Amidst Japan Covid-19 Toll; 107.50-109 Likely
The Dollar Yen pair was muted as FX volatility eased with the focus on the oil and asset markets. USD/JPY traded in a relatively narrow range of 107.514-107.937, finishing at 107.75 which is where it started yesterday. While the Yen is traditionally a safe-haven currency, the US Dollar has taken much of that away from the Japanese currency. Japan has also seen a setback in its battle against the Covid-19 outbreak with a rise in confirmed cases and related deaths. Japanese Prime Minister Shinzo Abe expanded a state of emergency to the whole country recently as the country rushed to expand testing.
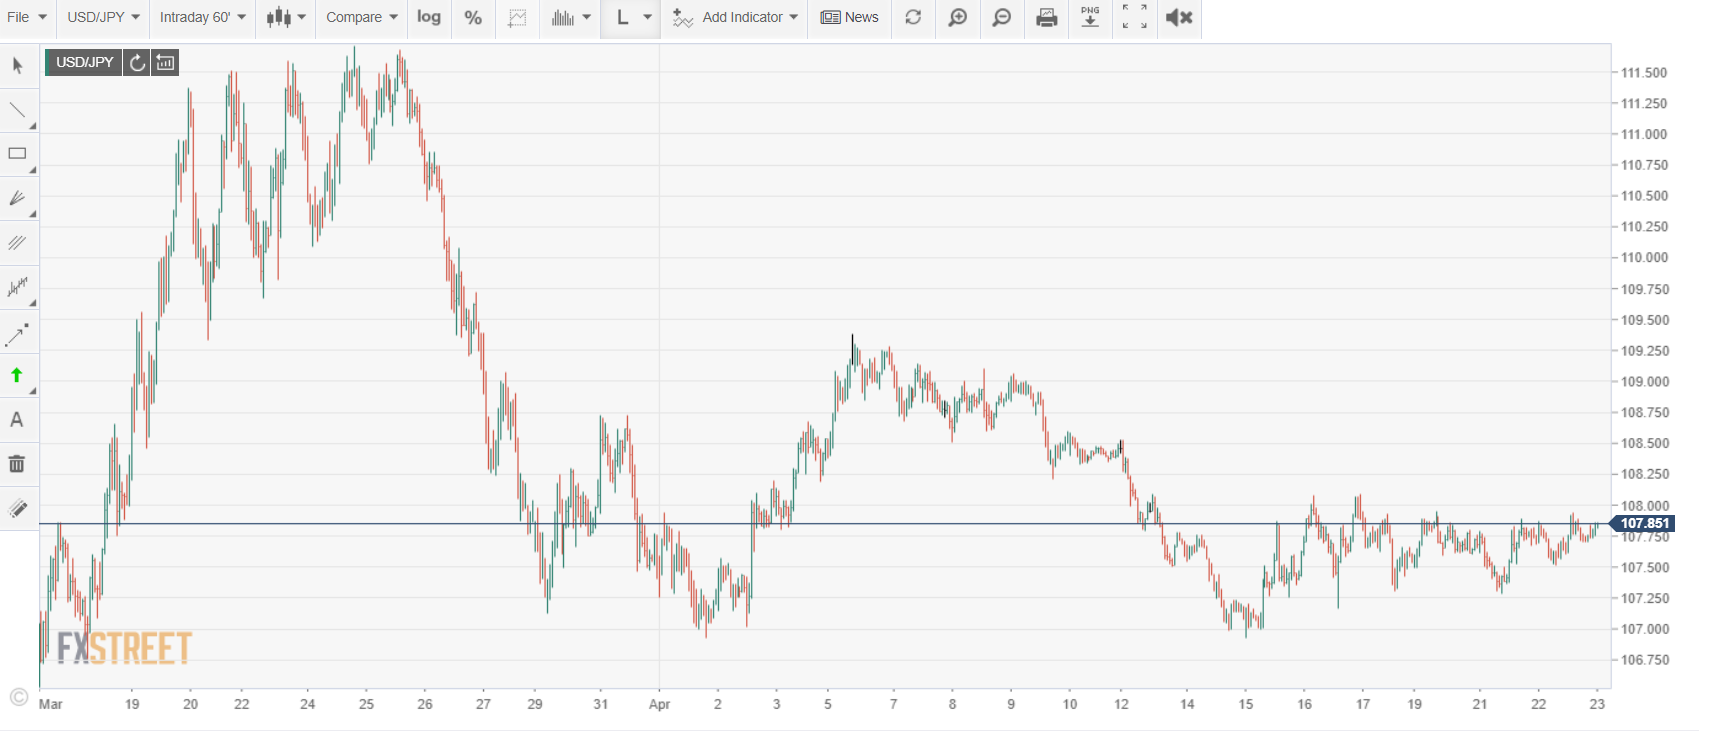
This is a real threat to the country and the economy and cannot be beneficial for the Japanese currency. USD/JPY has immediate resistance at 108.00 followed by 108.50 and 109.00. Immediate support can be found at 107.50 and 107.20. The latest Commitment of Traders report (week ended 14 April) saw net speculative JPY long bets at +JPY 22,645 (short USD), little changed from the previous week. Market positioning also supports a bid USD/JPY. Look to buy dips in a likely range today of 107.50-108.50. Expect volatility in this currency pair to pick up.
Reporting by Michael Moran. Filed 23 April 2020, 01:10 GMT.


