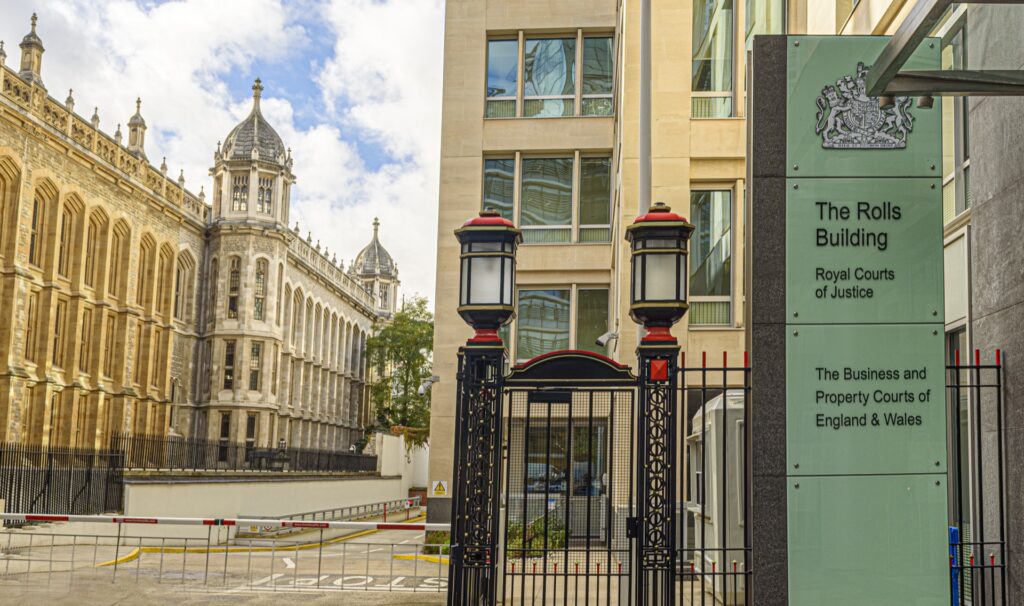
The Upper Tribunal has upheld the Financial Conduct Authority’s prohibition of Crispin Odey, holding that his removal of Odey Asset Management’s executive committee to stall his own disciplinary hearing was itself a failure of integrity under Individual Conduct Rule 1 — a finding that lands two weeks after the FCA’s non-financial misconduct rule took effect across every authorised UK firm.
In Robin Crispin Odey v The Financial Conduct Authority [2026] UKUT 00351 (TCC), released on September 14, 2026, a panel of Mr Justice Thompsell, Judge Rupert Jones and Member Catherine Farquharson dismissed Odey’s reference, upheld the prohibition order made under section 56 of the Financial Services and Markets Act 2000 (FSMA), and determined a financial penalty of £1,529,374 — down from the £1,835,200 the FCA had set in its Decision Notice. All five pleaded allegations were established. This analysis sets out what the Tribunal decided, how it compares with accountability regimes in Ireland, Singapore and Australia, and what owner-dominated brokers, prop firms and asset managers should take from it.
Key facts
- Citation and date: [2026] UKUT 00351 (TCC), released September 14, 2026. Hearings ran March 10–13, 16–20 and 24–26, plus May 5–6, 2026 (full decision, 229 pages).
- Rule breached: Individual Conduct Rule 1 (ICR1) in the Code of Conduct sourcebook — the duty to act with integrity. Odey was a certification employee, not an approved senior manager.
- Relevant Period: December 24, 2021 to November 17, 2022 (paragraph 2 of the decision).
- Penalty: £1,529,374 determined by the Tribunal, against £1,835,200 in the FCA’s Decision Notice. The Step 2 figure was 30% of relevant income of £2,548,957; the Tribunal declined the FCA’s 20% Step 3 uplift, leaving £764,687, then applied the Step 4 deterrence multiple of two (paragraphs 1373–1392).
- Firm-level rule breaches found: sections 63E and 63F FSMA (annual certification of fitness and propriety), SYSC 4.2.2R (a full-scope UK alternative investment fund manager must be managed by at least two persons), and FUND 3.7.2R (separation of risk and portfolio management).
- Scale context: OAM’s assets under management averaged about £2.925 billion in the Relevant Period; Odey’s own holdings in OAM funds were roughly £304 million (paragraph 1388).
- Regulatory backdrop: COCON 1.1.7FR, the FCA’s non-financial misconduct rule for non-bank firms, took effect on September 1, 2026 under PS25/23 — 13 days before the decision was released.
Methodology and sources
This analysis rests on the full 229-page Upper Tribunal decision in [2026] UKUT 00351 (TCC), read in the original, together with the FCA’s press release of September 14, 2026. Penalty figures were verified against the judgment text at paragraphs 1373 to 1392 and the disposition at paragraph 1408, not taken from secondary reporting. Handbook references are checked against the live FCA Handbook. Comparative material comes from primary regulator publications cited in the table below. The time window is the Relevant Period, December 24, 2021 to November 17, 2022, plus the rule changes effective September 1, 2026. One caveat: these are findings about one individual on one evidential record, and nothing here should be read as extending beyond what the decision states.
What the Tribunal actually decided
The FCA pleaded five allegations, each said to evidence a lack of integrity. The First was that Odey’s removal of both executive committees (ExCos) was deliberately intended to frustrate OAM’s disciplinary process and limit his personal accountability. The Second was that he showed reckless disregard for OAM’s governance and compliance with regulatory rules, causing the firm to breach regulatory obligations and risking its ability to meet the Threshold Conditions. The Third was that his conduct risked entrenching a culture that had normalised inappropriate behaviour towards female employees. The Fourth and Fifth, which the Tribunal called subsidiary, were that his dealings with OAM, its clients, its investors and the FCA lacked candour, and that he made a false assertion of fact to the FCA to secure an indefinite deferral of the hearing.
The Tribunal upheld all five. Its central factual finding, at paragraph 9, is that Odey’s asserted beliefs “were not the primary nor contemporaneous motives for his actions in removing the ExCos”; many he did not hold at the time, and those he did “were not reasonably held but reflected a warped set of values based on a strong sense of entitlement”. At paragraph 700 the panel described his contemporaneous complaints as “a smokescreen for his basic realisation that he was going to be held accountable for his actions with a likely outcome with which he disagreed”.
The structurally important holding is the Second Allegation. The Tribunal found that Odey “acted with reckless disregard for OAM’s governance and compliance with regulatory rules and obligations in removing both ExCos and lacked integrity in that way also” — a separate and freestanding route to the ICR1 breach. Having removed each committee, he installed himself as sole ExCo member, leaving OAM in breach of SYSC 4.2.2R’s requirement that a full-scope UK AIFM be managed by at least two persons; the guidance at SYSC 4.2.4G states that “at least two independent minds should” be applied. After the second removal, that ran from March 31, 2022 to July 4, 2022. Odey’s counsel argued these were at most technical breaches without crystallised harm. The Tribunal rejected that framing, recording the FCA witness observation that the sourcebook “is full of rules that in and of themselves are not harms, but are there in place to prevent harm”.
How four accountability regimes compare
| Jurisdiction / Regulator | Effective date | Scope | Key requirement | Penalty / sanction |
|---|---|---|---|---|
| UK (FCA) | ICR1 in force throughout; COCON 1.1.7FR from September 1, 2026 | All FSMA-authorised firms; conduct-rules staff and certification employees | Act with integrity (ICR1); SYSC 4.2.2R two-person management for full-scope UK AIFMs; ss.63E–63F FSMA annual certification | Prohibition under s.56 FSMA plus penalty under s.66; £1,529,374 in Odey |
| Ireland (Central Bank of Ireland) | Conduct standards and F&P amendments December 29, 2023; SEAR July 1, 2024; extended to INEDs July 1, 2025 | Credit institutions, investment firms holding client assets, insurers; controlled-function holders | Common Conduct Standards plus Additional Conduct Standards for senior executives; documented statements of responsibility under SEAR | Administrative Sanctions Procedure; prohibition notices under the Fitness and Probity regime |
| Singapore (MAS) | FSG-G22 from September 10, 2021; FSG-G01 applies continuously | Financial institutions, senior managers and material risk personnel | Five accountability and conduct outcomes; senior managers must be fit and proper (FSG-G01) — competent, honest, of integrity | Prohibition orders under the Financial Services and Markets Act 2022; licence conditions and revocation |
| Australia (ASIC / APRA) | Financial Accountability Regime from March 15, 2024 (ADIs); March 15, 2025 (insurance, superannuation) | Accountable persons — directors and senior executives of in-scope entities | Accountability statements plus obligations to act with honesty and integrity, due skill and co-operation | Disqualification of accountable persons; civil penalties against entities; deferred variable remuneration |
Sources: FCA Handbook and PS25/23; Central Bank of Ireland Guidance on the Standards of Fitness and Probity (November 2025); MAS Guidelines on Individual Accountability and Conduct; ASIC Financial Accountability Regime. Last updated: September 16, 2026.
The four regimes converge on personal accountability and diverge sharply on reach. The Irish and Australian frameworks are architectural: they map responsibilities to named individuals in advance, so an executive who dismantles the body he answers to leaves a documentary trail by design. Singapore’s approach under FSG-G22 is outcomes-based, leaning on the fit-and-proper criteria in FSG-G01. The UK sits between them, and the Odey decision matters because it shows the conduct rules reaching a person outside the senior-manager perimeter. He held no senior management function approval, and was subject to ICR1 as a certification employee. The lever the FCA used was not the Senior Managers Regime but the integrity limb of the conduct rules, applied to a controller acting through his ownership rather than any approved role. That is the regulatory-arbitrage point: a firm cannot insulate a dominant owner from conduct-rule liability by keeping him off the approved-persons list.
“Mr Odey clearly thought he could act with impunity. He twice sacked those tasked with protecting female employees from his inappropriate behaviour when they tried to hold him to account. He felt the rules shouldn’t apply to him and acted to save his own skin. During the hearing he reinvented history, painted himself as a victim and displayed no contrition. That arrogant entitlement and the resulting complete disregard for proper governance means Mr Odey is unfit to work in financial services.”
— Therese Chambers, executive director of enforcement and market oversight, Financial Conduct Authority (FCA press release)
Enforcement context and why the penalty fell
The FCA fined and banned Odey in 2025 following an investigation that also produced a separate outcome for the firm. Use of the integrity limb is not new: the regulator levied £446,800 over Dolfin Financial’s £25.2 million visa-scheme business, a case built on governance failures rather than a trading loss. The reference was a full rehearing, not a review, which is why the panel reconstructed the penalty from first principles under DEPP 6.5B rather than asking whether the FCA’s figure was reasonable.
The arithmetic is instructive. Step 1 produced no disgorgement. At Step 2 the FCA applied 30% of relevant income of £2,548,957, giving £764,687, on a level 4 seriousness assessment the Tribunal endorsed at paragraph 1372. At Step 3 the FCA added a 20% uplift for the aggravating factor in DEPP 6.5B.3G(2)(f) — that Odey had been told of the regulator’s concerns after the first ExCo removal and proceeded with the second anyway. The Tribunal accepted the factual predicate but declined the uplift, finding at paragraphs 1382 and 1383 that his co-operation and remediation “offsets the identified aggravating factor”, and noting the need “to avoid any double counting of factors which increased the seriousness of the breach and the allocation to level 4”. Step 4 then doubled the figure for deterrence, which the Tribunal upheld, citing OAM’s £2.925 billion average AUM and that the Step 3 figure would have been under 0.03% of it. No settlement discount applied.
The prohibition was addressed separately. Under section 133(6) FSMA the Tribunal does not itself impose a prohibition order; it decides whether to remit. At paragraphs 1395 and 1407 the panel held the order was reasonably imposed and appropriate, dismissed that part of the reference and refused to remit. The ban therefore stands unaltered while the penalty falls by £305,826.
What this means for brokers, prop firms and asset managers
The lesson for owner-dominated firms is narrow and severe. The Tribunal did not need to re-try the underlying conduct towards female employees to find a lack of integrity; the First and Second Allegations turn on what Odey did to the governance structure, and the Second stands on reckless disregard for regulatory obligations alone. For a proprietary trading group, a retail brokerage or a boutique manager where one person holds the equity and the commercial relationships, that is the exposure. Interfering with the body that supervises you — removing it, packing it, stalling it, or substituting yourself for it — is conduct in its own right, assessable even where it is brief and no client suffered.
Four operational consequences follow. For brokers, FCMs and introducing brokers: document the composition and quorum of any committee with disciplinary or conduct jurisdiction, and record who may change it and on what notice. A controller’s power to reconstitute governance belongs in the LLP agreement or articles, not in custom. For prop firms and CASPs with concentrated ownership: check whether the entity faces a two-person management requirement analogous to SYSC 4.2.2R, and treat any period of single-person control as a reportable breach, not an administrative gap. For fund managers and custodians: sections 63E and 63F FSMA require annual fitness-and-propriety certification, and the Odey record shows an unresolved disciplinary process can make certification impossible — which is itself the breach. For legal and compliance teams: the candour findings under the Fourth and Fifth Allegations are the quiet risk. What a firm tells the FCA about an internal process, and whether deferrals rest on accurate factual premises, is now reviewable at appellate level. The FCA’s increasingly gate-like approach to registration makes contemporaneous record-keeping cheap insurance.
“The reduction in the penalty is telling. This is the fifth time this year where an FCA penalty calculation has been lowered by the Tribunal. Here, the FCA was effectively trying to have its cake and eat it: it had already accounted for the seriousness of the conduct in pegging the misconduct at a level 4. However, it then sought a further 20% uplift for aggravating factors. The Tribunal rightly saw that for what it was, double counting.”
— Claire Cross, partner, Corker Binning, and a former senior lawyer in the FCA’s Enforcement Division (Insurance Edge)
What’s next — the forward view
Three threads run on from here. The first is the interaction between this decision and COCON 1.1.7FR, which from September 1, 2026 extends the conduct rules in non-bank firms to serious bullying, harassment and violence connected to an individual’s role. Odey was decided on integrity under ICR1, and the FCA’s published position is that the new rule is not retrospective. Clifford Chance’s regulatory team noted that “fitness and propriety assessments and the Conduct Rules serve different purposes” — a distinction the firm’s August 2026 briefing expects to be tested.
The second is penalty methodology. If Cross’s count is right that this is the fifth Tribunal reduction of an FCA penalty calculation this year, the pressure point is Step 3 of DEPP 6.5B and the boundary between factors that fix the seriousness level and those that aggravate on top of it. Firms negotiating with Enforcement now have an appellate authority for resisting an uplift built on a consideration already priced into the level.
The third is appellate. An Upper Tribunal decision in the Tax and Chancery Chamber may be appealed to the Court of Appeal with permission on a point of law, and no appeal had been reported as of September 16, 2026. Given the findings that Odey’s evidence lacked credibility, and that facts are not ordinarily reopened on appeal, the scope for challenge is narrow. Separately, whether other regulators replicate the FCA’s approach to governance interference — particularly those, like Ireland’s and Australia’s, keying accountability to prescribed roles rather than to conduct — is the comparative question worth watching into 2027.
TL;DR
The Upper Tribunal dismissed Crispin Odey’s reference on September 14, 2026 in [2026] UKUT 00351 (TCC), upholding the FCA’s section 56 FSMA prohibition and all five allegations that he lacked integrity under Individual Conduct Rule 1. Twice removing Odey Asset Management’s executive committee to stall his own disciplinary hearing, and installing himself as sole member in breach of SYSC 4.2.2R, was an integrity failure in its own right. The penalty was cut from £1,835,200 to £1,529,374 after the Tribunal refused the FCA’s 20% aggravating-factor uplift as double counting. OAM managed an average of £2.925 billion in the Relevant Period. Owner-dominated brokers, prop firms and managers should treat governance interference as assessable conduct, independent of the underlying behaviour.
FAQ
What did the Upper Tribunal decide in the Odey case?
It dismissed the reference in full. The panel upheld all five FCA allegations that Odey lacked integrity contrary to Individual Conduct Rule 1, upheld the section 56 FSMA prohibition and refused to remit it, and determined a penalty of £1,529,374. The decision, [2026] UKUT 00351 (TCC), was released on September 14, 2026 after hearings across March and May 2026.
Why was the fine reduced from £1.83 million to £1.53 million?
The Tribunal declined the FCA’s 20% Step 3 uplift under DEPP 6.5B.3G(2)(f). It accepted Odey had been warned after the first committee removal, but found his co-operation and remediation offset that aggravating factor, and that applying it risked double counting a consideration already reflected in the level 4 seriousness assessment. The Step 4 deterrence multiple of two was upheld.
Was Odey a senior manager under the Senior Managers and Certification Regime?
No. The decision records at paragraph 2 that he was a certification employee — a fund manager required to be certified annually as fit and proper — subject to Individual Conduct Rule 1 in that capacity. He held no senior management function approval, which is why the FCA proceeded on the conduct rules rather than the senior-manager standards.
Does the ruling depend on the findings about his behaviour towards female employees?
Not entirely. The First Allegation concerned his motive in removing the committees and the Second concerned reckless disregard for the firm’s governance and regulatory obligations, which the Tribunal found established as a freestanding route to a lack of integrity. The underlying behaviour supplied the context and the process he was avoiding, but the governance conduct was assessed on its own terms.
How do the new non-financial misconduct rules relate to this decision?
COCON 1.1.7FR took effect on September 1, 2026 under PS25/23, extending the conduct rules in non-bank firms to serious bullying, harassment and violence linked to a person’s role. Odey was decided under the pre-existing integrity rule, and the FCA states the new rule is not retrospective. The decision nonetheless shows conduct and culture questions were already reachable through integrity and fitness-and-propriety assessments.
What should firms with a dominant owner do in response?
Constrain, in constitutional documents rather than by convention, who may change the composition of any body with conduct or disciplinary jurisdiction. Treat any period of single-person management as a potential breach where a requirement such as SYSC 4.2.2R applies. Keep contemporaneous records of regulator communications, and build an escalation route for certifications stalled by an unresolved disciplinary matter.
Can the decision be appealed?
An Upper Tribunal decision may be appealed to the Court of Appeal with permission, but only on a point of law, and no appeal had been reported as of September 16, 2026. Because the Tribunal made extensive adverse credibility findings, and facts are not ordinarily reopened on appeal, the available grounds would be limited.
This article is informational analysis only and does not constitute legal, regulatory, tax, or investment advice. Regulatory frameworks change frequently and interpretation depends on facts and circumstances; primary documents and official regulator guidance always supersede summaries. Firms should consult qualified legal counsel and their relevant supervisory authority before taking any action based on the analysis above.
Rick Steves
Rick Steves has seen business and economics through many lenses. He joined the financial services industry in 2009, and has been a financial journalist since 2011. He holds a degree in Business Administration and has experience producing real-time news, from both buy-side and sell-side, as well as for retail traders, brokers and service providers. Steves' work has appeared in a variety of online publications including FX Street, NewsBTC, FinanceFeeds, and The Industry Spread. Rick has great interest in the dynamics of the trading industry. The never-ending clash between technology, economics, regulation, and more importantly, the people.
