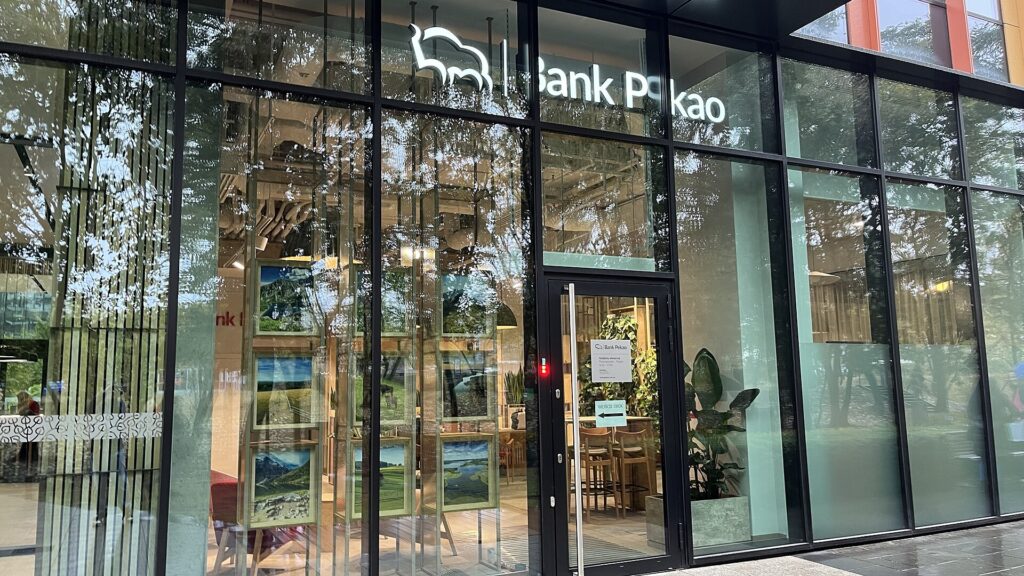
Bank Pekao S.A. has picked NCR Atleos’s Authentic platform as the payment switch for its card processing, handing one of the most sensitive pieces of plumbing at Poland’s second-largest universal bank to an outside vendor. The timing is the story. The deal lands weeks after Pekao reported that an increase in its corporate income tax rate to 30% from 19% had pushed first-half profit down, which makes a bought-in payment switch look less like a technology refresh and more like a cost lever.
What Bank Pekao is buying
According to the NCR Atleos announcement issued via Business Wire on September 17, 2026, Atleos will supply the Authentic switch to run Bank Pekao’s card payment processing operations and “future innovation objectives” as part of a wider modernisation of the bank’s card infrastructure. Neither party disclosed the contract value, the implementation timeline or which legacy system the new payment switch replaces.
A payment switch sits between card schemes, ATMs, point-of-sale acquiring and the issuer’s authorisation systems, routing every card transaction to the right place in milliseconds. Trade outlet ATM Marketplace reported that Authentic can process more than 10,000 transactions per second, alongside card management, Application Programming Interface (API) workflows, PIN management and fraud detection.
“After a comprehensive evaluation process, we selected the Authentic platform because of its proven capabilities, flexibility and strong track record supporting payment modernization initiatives at financial institutions around the world,” said Maciej Jopyk, CIO and head of IT at Bank Pekao S.A. Bartłomiej Śliwa, Area Vice President for Central and Eastern Europe at Atleos, called the agreement “an important milestone” and said Pekao “provides an outstanding example for organizations pursuing similar transformation initiatives.”
Why a payment switch matters to Pekao’s numbers
Pekao’s own first-half 2026 results, published on July 30, 2026, explain why infrastructure spend is under scrutiny. Net profit fell to PLN 2.75 billion from PLN 3.29 billion a year earlier, which the bank attributed to the tax increase, lower market interest rates and a PLN 84 million rise in Bank Guarantee Fund contributions. Net interest income slipped to PLN 6.61 billion from PLN 6.86 billion.
Put those figures next to the bank’s 2027 strategy targets and the switch decision reads differently. Pekao is aiming for a cost-to-income ratio below 35%; including the annualised Bank Guarantee Fund charge it stood at 36.4% in the first half. With interest income shrinking, fee income is doing more of the work: it rose 11% year on year to PLN 1.66 billion, and card activity is one of the few fee lines a bank can grow through its own processing stack. A switch that is cheaper to run and quicker to extend feeds both sides of that ratio.
The bank is also chasing digital scale. It reported 3.84 million active mobile banking users at the end of June against a 2027 target of 4.4 million, and said a third of new accounts were opened by people aged up to 26. Pekao already bundles payment rings into its travel offer, and each new card form factor depends on the switch underneath.
Rival vendors are chasing the same budgets
On the same day as the Pekao announcement, ACI Worldwide expanded its ACI Connetic platform with a cloud-native financial messaging layer, pitching banks on decoupling messaging from core payment processing. “Financial messaging is the connective tissue of modern payments,” said Craig Ramsey, global head of account-to-account payments at ACI Worldwide. ACI said banks in the UK and Europe are adopting Connetic to unify processing across schemes.
The two pitches split the market in a useful way. ACI is selling a cloud-native, rail-agnostic layer aimed at real-time and ISO 20022 traffic, while Atleos is winning on a card-centric switch with a long installed base. Pekao chose the card path, which suggests Polish issuers still see card volumes, not account-to-account rails, as the near-term profit engine. Issuer-processor challengers such as Paymentology are pushing API-first processing to fintechs, but a bank of Pekao’s size, with assets of PLN 368 billion, has so far bought from the incumbents.
The pattern echoes other large European lenders moving critical systems to external platforms, from Intesa Sanpaolo’s core banking move to Google Cloud to earlier vendor pushes into the region such as Temenos’s SaaS expansion in Poland and Romania.
What happens next
Switch migrations are slow because every card authorisation must keep flowing during cutover, so the first real signal will be a go-live date. Atleos said the deal strengthens its Central and Eastern Europe presence and points to “growing demand” among banks replacing legacy processing. If the higher tax rate squeezes other Polish lenders the way it squeezed Pekao, expect at least one more large regional issuer to announce a payment switch tender within the next year.
Rick Steves
Rick Steves has seen business and economics through many lenses. He joined the financial services industry in 2009, and has been a financial journalist since 2011. He holds a degree in Business Administration and has experience producing real-time news, from both buy-side and sell-side, as well as for retail traders, brokers and service providers. Steves' work has appeared in a variety of online publications including FX Street, NewsBTC, FinanceFeeds, and The Industry Spread. Rick has great interest in the dynamics of the trading industry. The never-ending clash between technology, economics, regulation, and more importantly, the people.
