The Securities and Exchange Commission’s (SEC) Innovation Exemption, issued on September 17, 2026 as Exchange Act Release No. 34-106402, opens the first US route for on-chain secondary trading of real listed equities: capped at 75 large-cap and 250 other symbols, confined to permissioned automated market makers, sunsetting on September 17, 2031, and closed to synthetic tokens of the kind much of the offshore market sells today.
The SEC’s 60-page order under Section 36(a)(1) of the Securities Exchange Act of 1934 exempts “Tokenized Securities Venues” (TSVs) from the definition of “exchange” in Section 3(a)(1) and exempts certain liquidity providers from the definition of “dealer” in Section 3(a)(5), both until September 17, 2031. The volume ceilings are tight: 0.25% of prior-month average daily share volume for Tier 1 names and 2.5% for Tier 2. This analysis walks through the conditions, the caps, the sunset, the comment file and the firms left outside it, and compares the order with the EU, UK and Swiss regimes.
Key facts
- Release No. 34-106402, comment file No. 4-927, dated September 17, 2026; 60 pages; relief effective from September 17, 2026 until September 17, 2031 (SEC order, Sections V and VII).
- Tier 1 (S&P 500, Russell 1000 and eligible exchange-traded products): maximum 75 symbols and 0.25% of prior-month average daily share volume per stock (order, Section II.F).
- Tier 2 (all other NMS stock except rights and warrants): maximum 250 symbols and 2.5% of prior-month average daily share volume (order, Section II.F).
- A second volume breach in the same stock forces an immediate three-month pause in that symbol; symbol-count breaches get no grace (order, Section II.F and note 74).
- A TSV must publish a public notice at least 30 calendar days before operating and email the SEC within one business day (SEC fact sheet).
- Excluded: tokens in which “a third party issues a crypto asset representing its own security that provides synthetic exposure”, including tokenized linked securities and tokenized security-based swaps (order, Section I).
Methodology and sources
This analysis rests on three SEC primary documents read in full: the exemptive order (Release No. 34-106402), the fact sheet and Press Release 2026-90. It also uses same-day statements by Chairman Paul S. Atkins, Commissioner Hester M. Peirce and Commissioner Mark T. Uyeda, client memos from Sullivan & Cromwell and Dechert, and ESMA, UK and FINMA primary sources for the comparison. The window is July 2020 to September 22, 2026. Every quotation was checked word for word against the page linked. Where the piece does its own arithmetic, it says so.
What order 34-106402 actually permits, and on what terms
The order builds a new category rather than bending an old one. Because a TSV that meets the conditions is not an exchange, it is not a trading centre under Regulation NMS, so Rule 611 order protection, Rule 602 quote dissemination and Rule 612 tick sizes do not bind it. The order concedes that AMM pricing, which is set by the ratio of assets in a pool, “may be unable to comply” with Rule 611.
The Innovation Exemption is a conditional, time-limited carve-out from the definitions of “exchange” in Section 3(a)(1) and “dealer” in Section 3(a)(5) of the Securities Exchange Act of 1934. It lets a US-person venue run permissioned AMM liquidity pools in tokenised NMS stock until September 17, 2031, without registering as a national securities exchange or operating as an alternative trading system. Eligible tokens are shares tokenised by the issuer, or by an unaffiliated third party, that carry the same interest, dividends, voting rights and liquidation claim as the underlying NMS stock. Each token must trade in a pair against another tokenised NMS stock, a non-security crypto asset such as a payment stablecoin, or a tokenised money market fund. Per Release No. 34-106402, venues face symbol caps of 75 (Tier 1) and 250 (Tier 2), must halt when the primary listing exchange halts, may not offer leverage, and must publish US dollar trade data within 10 minutes.
The operating conditions come in 12 lettered blocks (Sections II.A to II.L). Smart contracts must be “auditable, public, and deployed on a public, permissionless distributed ledger”, although the pool itself can be permissioned: note 55 of the order says a permissioned AMM pool “can be deployed on ‘permissionless’ blockchain.” The TSV must be a US person and so fall under Office of Foreign Assets Control (OFAC) sanctions obligations. No primary issuance is allowed on the venue. A TSV cannot borrow, hypothecate or extend credit to buy tokens. It may not describe itself as “registered”, “approved” or “endorsed”. It must keep books and records for three years after the exemption ends and consent to SEC staff examination “at any time”.
Transparency replaces much of Regulation NMS. A TSV must publish free, machine-readable, US dollar-denominated data for every trade in the past 30 days, updated within 10 minutes and time-stamped in UTC, together with pool contract addresses, daily pair volume and end-of-day pool size. When a primary listing exchange halts or suspends a stock, the TSV must “stop trading in a Tokenized NMS Stock concurrently”, which covers market-wide circuit breakers and news-pending halts. A “significant operational event”, such as a system intrusion, must be reported to participants immediately and to the SEC “promptly.”
Third-party tokens come with an issuer veto. Before listing a stock tokenised by an unaffiliated party, the TSV must send written notice to the issuer, and trading cannot begin until 30 calendar days after the issuer receives it. An objection lodged on or before day 30 blocks that stock on that venue. The third party must also pass proxy materials through “at no cost to the issuer or the shareholders.” The SEC’s separate proposal to let a distributed ledger serve as the share register deals with the record-keeping side of the same problem.
“Today, the Securities and Exchange Commission is taking a significant step forward, within its statutory authority, to bring America’s capital markets into the digital age by facilitating onchain trading of certain tokenized stocks through the ‘Innovation Exemption.'”
— Paul S. Atkins, Chairman, US Securities and Exchange Commission (SEC Press Release 2026-90)
How the 75- and 250-symbol caps and the volume brakes work
The tiers borrow the Limit Up-Limit Down (LULD) Plan, approved as a pilot in 2012 and made permanent in 2019. Tier 1 covers S&P 500 and Russell 1000 constituents plus exchange-traded products with more than $2,000,000 in notional consolidated average daily volume. Tier 2 is everything else except rights and warrants. The test divides a token’s average daily volume on the TSV by the stock’s average daily volume on the consolidated tape. Affiliated TSVs must add their volumes and symbol counts together, to stop firms splitting “into multiple TSVs to avoid triggering the volume and symbol limitations.”
Footnote 72 of the order gives the scale. SEC staff calculated 2025 daily weighted average volume at 3,022,668 shares for LULD Tier 1 stocks and 1,207,978 shares for Tier 2. On our arithmetic, the caps allow roughly 7,557 shares a day in an average Tier 1 name (0.25%) and about 30,199 shares a day in an average Tier 2 name (2.5%). The order’s stated purpose is to limit “the potential impact of any price dislocations” between the token and the stock while the SEC studies the model.
Enforcement of the caps is stepped. The first time a venue exceeds the volume threshold in a stock, it only has to stay under it from then on. Each later breach triggers an immediate three-month pause in that stock across all affiliated TSVs, notice to participants and a revised public notice within five business days. Venues may pause voluntarily as they approach a threshold. The grace applies only to volume: under note 74, a TSV that exceeds the symbol limit “would not meet the conditions of the TSV Exemption.”
How the US model compares with the EU, UK and Swiss regimes
| Jurisdiction / Regulator | Effective date | Scope | Key requirement | Supervisory lever |
|---|---|---|---|---|
| US (SEC) — Innovation Exemption | September 17, 2026 to September 17, 2031 | Tokenised NMS stock on permissioned AMM pools; US-person TSVs | Release 34-106402 Section II.F: 75 Tier 1 / 250 Tier 2 symbols; 0.25% / 2.5% of prior-month average daily volume | Exemption lost for the stock; three-month pause on repeat volume breach; notice warns of enforcement action (Section III.b) |
| EU (ESMA / national authorities) — DLT Pilot Regime | March 23, 2023; runs at least three years | DLT MTFs, DLT settlement systems and combined DLT TSSs under Regulation (EU) 2022/858 | Shares with market capitalisation below €500 million; bonds under €1 billion issuance; UCITS below €500 million assets | National authorities grant specific permissions; ESMA publishes each permission and the exemptions granted |
| UK (Bank of England / FCA) — Digital Securities Sandbox | January 8, 2024 (SI 2023/1398) | Recognised exchanges, CSDs, MTF and OTF operators, and others the regulator admits (Regulation 3) | Activity limits calibrated by asset type under a modified legal regime | Glidepath: higher limits only after passing compliance gates |
| Switzerland (FINMA) — DLT trading facility | DLT Act in force August 1, 2021; first licence March 18, 2025 | Multilateral trading of DLT securities under Article 73a ff. of the Financial Market Infrastructure Act (FinMIA) | “Small” DLT facilities must stay under thresholds in the Financial Market Infrastructure Ordinance (FinMIO) | FINMA licence; source-code checks on smart contracts |
Sources: SEC Release 34-106402; ESMA DLT Pilot Regime; SI 2023/1398; Bank of England DSS; FINMA, March 18, 2025. Last updated: September 23, 2026.
The four regimes all cap activity, but they cap different things. The SEC caps a venue’s share of trading in each stock and the number of stocks it lists. The UK caps total activity per asset type and raises the ceiling as firms pass gates. Switzerland licenses a separate class of infrastructure and offers lighter rules to small facilities.
The SEC’s volume-share cap on tokenised NMS stock is a dual ceiling: a venue may list no more than 75 Tier 1 and 250 Tier 2 symbols, and its daily volume in each token may not exceed 0.25% (Tier 1) or 2.5% (Tier 2) of the underlying stock’s prior-month average daily share volume on the consolidated tape. Release No. 34-106402 sets these limits in Section II.F and requires affiliated venues to aggregate both measures. The design differs from the EU’s DLT Pilot Regime under Regulation (EU) 2022/858, which restricts eligible shares to issuers below €500 million in market capitalisation. The US approach therefore admits Apple-scale names but keeps each token’s footprint small, while Europe admits only small issuers and places no per-stock share cap on them. For a venue operator, the practical effect is that US revenue scales with the number of symbols listed rather than with depth in any one of them, because depth is capped from day one.
The arbitrage risk runs in one direction. Large-cap US equity tokens can now trade onshore, with limits, which the EU regime cannot offer at all, while synthetic exposure to the same stocks stays offshore. Our June comparison of tokenised securities rules across the EU, UK, US and Singapore described the US as “same rules, new plumbing”. The US now has a bespoke venue category, but only for AMMs: Sullivan & Cromwell notes that it “appears not to cover” a standalone central limit order book protocol.
Who is excluded: synthetics, security-based swaps and order books
The exclusion is written into the definition. Tokenized NMS Stock “does not include securities where a third party issues a crypto asset representing its own security that provides synthetic exposure to an underlying security, such as a tokenized linked security or a tokenized security-based swap.” Rights and warrants are also excluded, and the order grants no relief under the Investment Company Act of 1940, which leaves tokenised ETF shares uncertain. In July we reported that the SEC’s delay was splitting synthetic tokens from real ones. In May, Commissioner Peirce signalled that the exemption would stop at digital twins. The final text confirms both readings.
“some popular tokenization structures deployed outside of the United States – such as ‘synthetic’ stock taking the form of equity-linked debt or derivatives – will not be eligible.”
— Sullivan & Cromwell LLP, client memo, September 18, 2026 (Sullivan & Cromwell)
Any offshore product structured as the platform’s own certificate or note that tracks a share, rather than as the share itself, falls into the excluded bucket. That includes xStocks-style offerings built this way. Such products can still reach US investors only through registration or another exemption. The venue relief does not help them. Kraken’s parent has already taken xStocks to Hong Kong, the UK and Seoul, and the London Stock Exchange handed tokenised equity distribution to Kraken. Those non-US routes remain the growth path for the synthetic model.
Enforcement context: Abra and Terraform define the excluded bucket
The exclusion follows cases the SEC has already brought. On July 13, 2020, the SEC charged Abra and Plutus Technologies Philippines Corp. over an app that let users take “synthetic exposure to price movements of stocks and exchange-traded fund (ETF) shares trading in the U.S.” The order found the contracts were security-based swaps offered to retail users without registration and without being transacted on a registered national exchange. Without admitting or denying the findings, the firms accepted a cease-and-desist order and a combined $150,000 penalty, and the Commodity Futures Trading Commission (CFTC) settled a parallel action (SEC Press Release 2020-153). Moving the counterparty offshore did not change the outcome. The SEC’s Daniel Michael said firms “may not evade the federal securities laws merely by transacting primarily with non-U.S. retail investors.”
The larger precedent is Terraform Labs. The SEC’s February 16, 2023 complaint in the Southern District of New York described Mirror Protocol “mAssets” as “security-based swaps designed to pay returns by mirroring the price of stocks of US companies” (SEC Press Release 2023-32). After a jury found Terraform and Do Kwon liable for fraud on April 5, 2024, the June 13, 2024 settlement required Terraform to pay a $420,000,000 civil penalty on top of $3,586,875,883 in disgorgement and $466,952,423 in prejudgment interest, and Kwon to pay an $80,000,000 penalty (SEC Press Release 2024-73). The new order does nothing to undo the classification of stock mirrors as swaps.
What this means for venues, brokers, liquidity providers and compliance teams
Venue operators. The earliest date a TSV can operate is 30 calendar days after it posts its public notice. A notice posted on September 17 means October 17, 2026. The notice covers some 30 lettered disclosure items, from governance and LP-token rights to fees, market-data use, systems safeguards and whether the venue is the exclusive or predominant market for a token. It must say that the TSV is not subject to fair-access rules or Regulation NMS. A registered firm may run a TSV only through an affiliate kept separate from its registered business.
Brokers. Sullivan & Cromwell warns that a broker-dealer trading on a TSV “would remain subject to best execution and reporting requirements”. Question 7 of the order asks whether broker-dealer participants need their own Regulation NMS relief.
Liquidity providers. A “Covered Firm” gets a separate exemption from the definition of dealer, but only if it trades for its own account, holds no customer assets, keeps records showing it has liquid assets to cover losses, states publicly that it is not a registered broker-dealer and discloses any incentives it receives. Its securities activity must be limited to AMM pools run under the TSV exemption.
Compliance teams. The main workloads are wallet allow-listing, OFAC screening, volume monitoring and 10-minute trade reporting. A firm that outsources permissioning remains responsible for it under note 31 of the order.
“The notice in effect substitutes a disclosure regime for many of the substantive regulatory requirements of the exchange regulatory framework.”
— Dechert LLP, OnPoint client alert, September 21, 2026, key contacts including partners Brenden P. Carroll and Mark D. Perlow (Dechert)
The sceptical reading is that disclosure and caps take the place of fair-access and order-protection duties that investors in listed stocks have long relied on. The SEC’s answer is that the caps keep the experiment too small to damage price discovery. Commissioner Peirce drew the boundary on the other side: “This order is not about decentralized finance. Truly decentralized systems that are driven by automated software do not give rise to the foundational concerns underlying securities regulation, namely that an intermediary you trust to act on your behalf will be foolish, careless, or compromised” (Peirce statement).
What’s next: comment file 4-927, the 2031 sunset and the rulemaking behind it
The order asks 10 questions. They include whether either exemption should become permanent, whether the Tier 1 and Tier 2 limits are right, whether TSVs should trade securities beyond Tokenized NMS Stock, and how 10-minute reporting and overnight trading could affect exchange opening and closing auctions. Comments go to File No. 4-927 through the SEC form or rule-comments@sec.gov. The order sets no closing date, so the file stays open while the SEC monitors use. Commissioner Uyeda asked for evidence: “Detailed, data-supported comments—ideally including metrics, case studies, incident analyses, and operational narratives from live or test environments—can help evaluate tradeoffs and shape future proposals.”
Three other timelines run alongside the comment file. The SEC’s June 11, 2026 proposal to rescind the Rule 611 trade-through rule (Release No. 105655, cited in note 33) would remove one reason TSVs needed an exemption at all. Note 114 says the Division of Trading and Markets is considering amendments to the scope of the term “dealer”. And DTCC’s October tokenisation launch runs on its own three-year clock. Chairman Atkins called the order an interim step that “must be followed by durable rulemaking”, noting that Congress “was unsuccessful in advancing the CLARITY Act” the same week. The SEC can change the exemptions at any time before September 17, 2031 under Section 36.
TL;DR
SEC Release No. 34-106402, issued September 17, 2026, lets US-person Tokenized Securities Venues run permissioned AMM pools in real tokenised NMS stock without registering as exchanges, and lets proprietary liquidity providers operate without registering as dealers, until September 17, 2031. Each venue is capped at 75 Tier 1 and 250 Tier 2 symbols and at 0.25% or 2.5% of each stock’s prior-month average daily volume. SEC staff put 2025 Tier 1 daily weighted average volume at 3,022,668 shares. Venues must give 30 days’ public notice, respect a 30-day issuer veto on third-party tokens, halt with the listing exchange and publish trades within 10 minutes. Synthetic tokens, tokenised security-based swaps, rights and warrants are excluded. Comments are open under File No. 4-927.
FAQ
What is a Tokenized Securities Venue?
A Tokenized Securities Venue is a person or group that brings together buyers and sellers of tokenised NMS stock by providing AMM liquidity pools for permissioned participants and by setting access standards. Under SEC Release No. 34-106402, a TSV that meets every condition is exempt from the definition of “exchange” until September 17, 2031. It must be a US person, deploy auditable public smart contracts on a permissionless ledger, and publish a public notice at least 30 calendar days before it begins operating.
Which stocks can trade under the Innovation Exemption?
Only NMS stocks tokenised by the issuer, or by an unaffiliated third party, that give holders the same interest, dividends, voting rights and liquidation claim as the traditional shares. Tier 1 covers S&P 500 and Russell 1000 constituents and eligible ETPs; Tier 2 covers other NMS stock. Rights and warrants are excluded. Each token must trade in a pair with another tokenised NMS stock, a non-security crypto asset such as a payment stablecoin, or a tokenised money market fund.
Are xStocks and other synthetic stock tokens covered?
Not if they are structured as the platform’s own security providing synthetic exposure. The order excludes tokens where “a third party issues a crypto asset representing its own security that provides synthetic exposure to an underlying security”, naming tokenised linked securities and tokenised security-based swaps. Products built as tracker certificates, equity-linked notes or swaps therefore need registration or another exemption to reach US investors. The SEC’s 2020 Abra settlement, a $150,000 penalty, shows how it treats synthetic stock contracts.
What happens if a venue breaches the volume cap?
The first breach in a given stock requires no action beyond staying under the threshold afterwards. Each subsequent breach forces an immediate three-month pause in that stock across the TSV and its affiliated venues, immediate notice to participants and a revised public notice within five business days. The grace applies only to volume. Exceeding the 75 Tier 1 or 250 Tier 2 symbol limit means the venue no longer meets the exemption’s conditions.
Can an issuer stop its shares being tokenised and traded?
Yes, for third-party tokens. A TSV must send written notice to the issuer’s principal executive offices before listing a stock tokenised by an unaffiliated party, and trading cannot start until 30 calendar days after receipt. If the issuer objects on or before day 30, the TSV cannot list that token and must disclose the objection within five business days. Dechert notes that the mechanism matters to ETF sponsors.
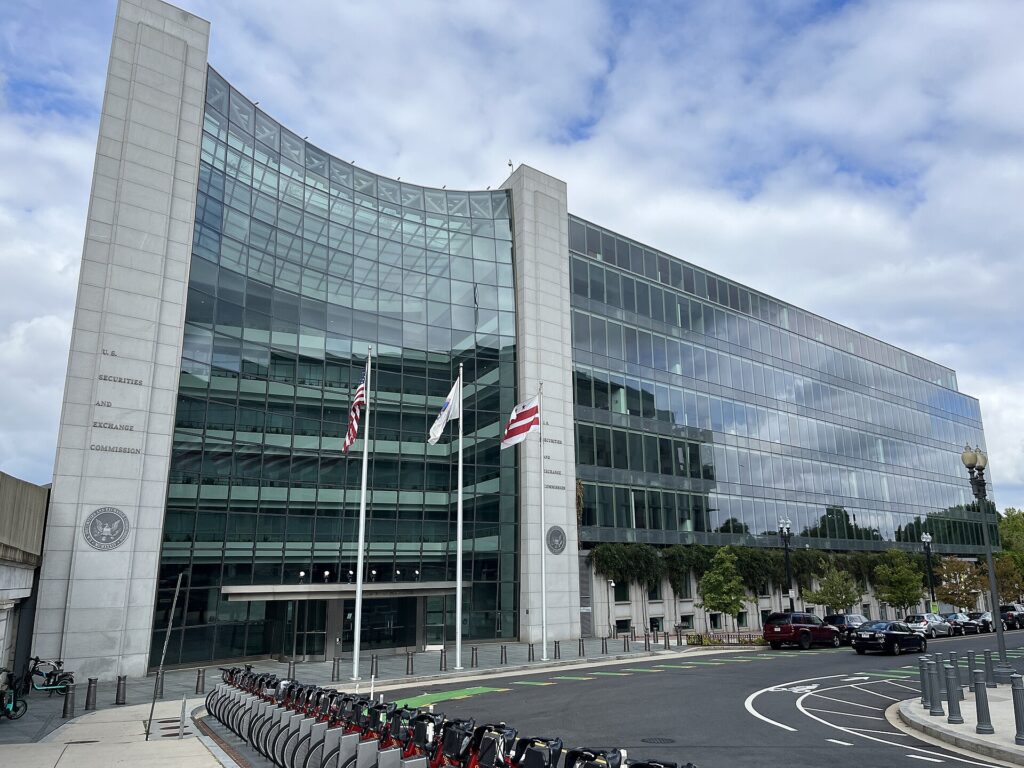
Featured image: US Securities and Exchange Commission headquarters, 100 F Street NE, Washington, DC. Photo by Another Believer via Wikimedia Commons, CC BY-SA 4.0.
This article is informational analysis only and does not constitute legal, regulatory, tax, or investment advice. Regulatory frameworks change frequently and interpretation depends on facts and circumstances; primary documents and official regulator guidance always supersede summaries. Firms should consult qualified legal counsel and their relevant supervisory authority before taking any action based on the analysis above.
Rick Steves
Rick Steves has seen business and economics through many lenses. He joined the financial services industry in 2009, and has been a financial journalist since 2011. He holds a degree in Business Administration and has experience producing real-time news, from both buy-side and sell-side, as well as for retail traders, brokers and service providers. Steves' work has appeared in a variety of online publications including FX Street, NewsBTC, FinanceFeeds, and The Industry Spread. Rick has great interest in the dynamics of the trading industry. The never-ending clash between technology, economics, regulation, and more importantly, the people.
