Risk-On, Risk-Off, US Dollar Pares Losses, Stocks Reverse Gains
Risk-On, Risk-Off, US Dollar Pares Losses, Stocks Reverse Gains AUD Climbs, RBA Stands Pat, EUR, GBP, CAD, EMS Rally

Summary: It was a case of risk-on, risk-off as markets tried to get a feel of the overall Covid 19 impact even as the pandemic’s curves gave signs of flattening. The US Dollar fell against its rivals, including the risk and Emerging Market currencies, paring losses at the New York close. Wall Street stocks slid, erasing sharp gains to close in the negative. The build in risk appetite fizzled with no immediate end in sight for the current crisis based on mixed headlines. The Australian Dollar soared to 0.62080 overnight and one-week highs (0.6091) after the RBA kept its key interest rate unchanged at all-time lows of 0.25%. AUD/USD eased to 0.6172 in late New York. The Euro rallied 0.86% to 1.0894 (1.0795) on the broad-based US Dollar weakness. Sterling advanced to 1.2335 from 1.2245, shrugging-off reports that UK Prime Minister Boris Johnson was transferred to the intensive care unit due to persistent coronavirus symptoms. UK Covid-19 cases slowed for the second day while fatalities remain low. Against the Canadian Dollar, the Greenback slid to 1.39454, near 2-week lows, before rallying at the NY close to settle at 1.4013. Brent Crude Oil prices slid 2% (USD 32.40) as supplies swelled and expectations for an agreement on output cuts between major producers dwindled. The USD/JPY pair eased to 108.81 from 109.18.
In late New York trade, the DOW erased earlier gains, finishing down 0.21% to 22,555. The S&P 500 lost 0.38% to 2645. Global bond yields climbed. The benchmark US 10-year bond yield ended 4 basis points higher at 0.71%. Germany’s 10-year Bund gained 12 basis points to -0.32%. Australian 10-year bond yields were at 0.90% from 0.76% yesterday.
Data released yesterday saw Japan’s Household Spending dip to -0.3%, bettering forecasts at -3.3%. Australia’s Trade Balance rose to +AUD 4.36 billion, beating median estimates of +AUD 3.75 billion.
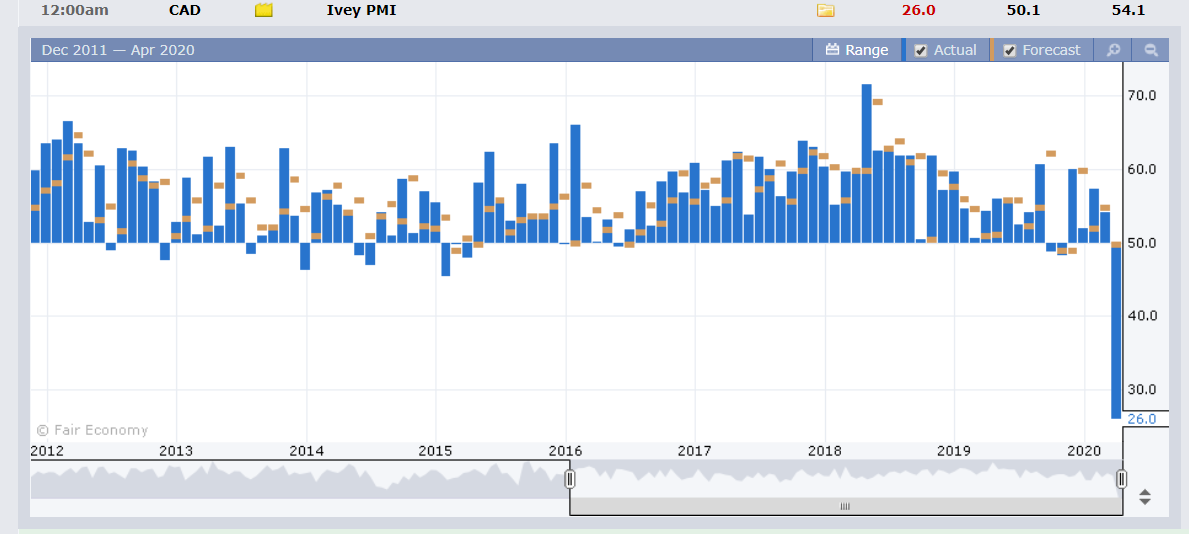
German Industrial Production climbed to 0.3% in March from an upwardly revised 3.2% the previous month, beating expectations of -0.7%. Canada’s IVEY March PMI slumped to 26.0 from 54.1, underwhelming forecasts of 50.1. US JOLTs Job Openings climbed to 6.88 million, better than forecasts of 6.55 million from an upwardly revised 7.01 million.
On the Lookout: Uncertainty continued to dominate trade into a shortened trading week ahead of the long Easter break which begins on Good Friday. Volatility stayed high. Despite growing signs of a slowing on the Covid-19 contagion, the market’s risk-on mode evaporated at the New York close. Global leaders continue to look at additional stimulus support measures.
With liquidity thinning into the weekend, we can expect higher volatility in FX.
Today’s economic calendar is light. The main event comes in at the end of the North American trading day which is the release of the Fed’s FOMC Minutes.
Japan kicks off with its Core Machinery Orders, Current Account and Economic Watchers Sentiment. Australia reports its Home Loans data for February. Canadian data follow with Housing Starts (March) and Building Approvals (February).
Trading Perspective: The Dollar Index (USD/DXY) retreated after hitting 100.931 yesterday, just below the resistance level of 101.00. This coincides with a EUR/USD base at 1.07727 Tuesday night. The Euro takes virtually 60% of the weight in the Dollar Index.
As we approach the Easter weekend, market positioning will be a key factor with expected high volatile trade. We highlighted the net speculative USD shorts increased as a result of a strong build in Euro long bets which totalled the biggest since June 2018.
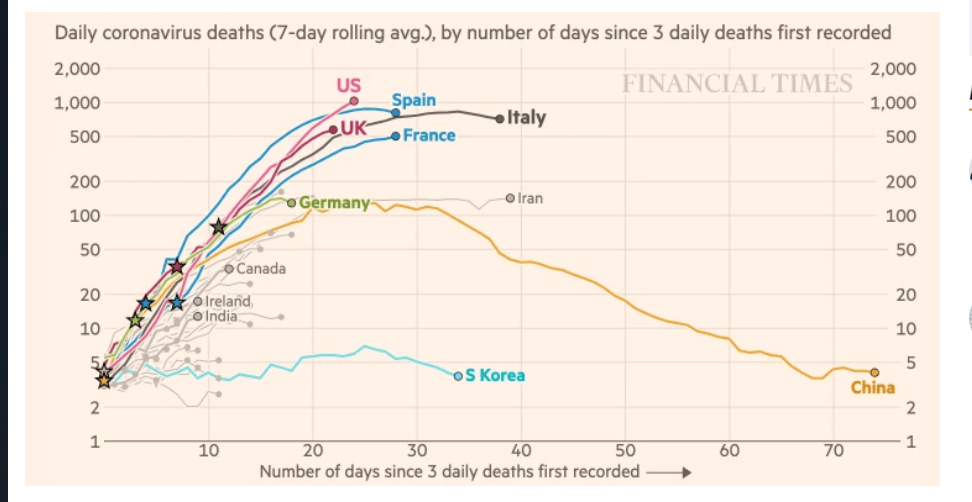
While Covid-19 pandemic may be easing off in parts of the world, other parts (Japan, Asia) are still unknown and the crisis is still far from over. This will continue to be USD supportive.
USD/CAD – Risk-On Lifts the Loonie, Lower Oil weighs, 1.3980-1.4130 Likely
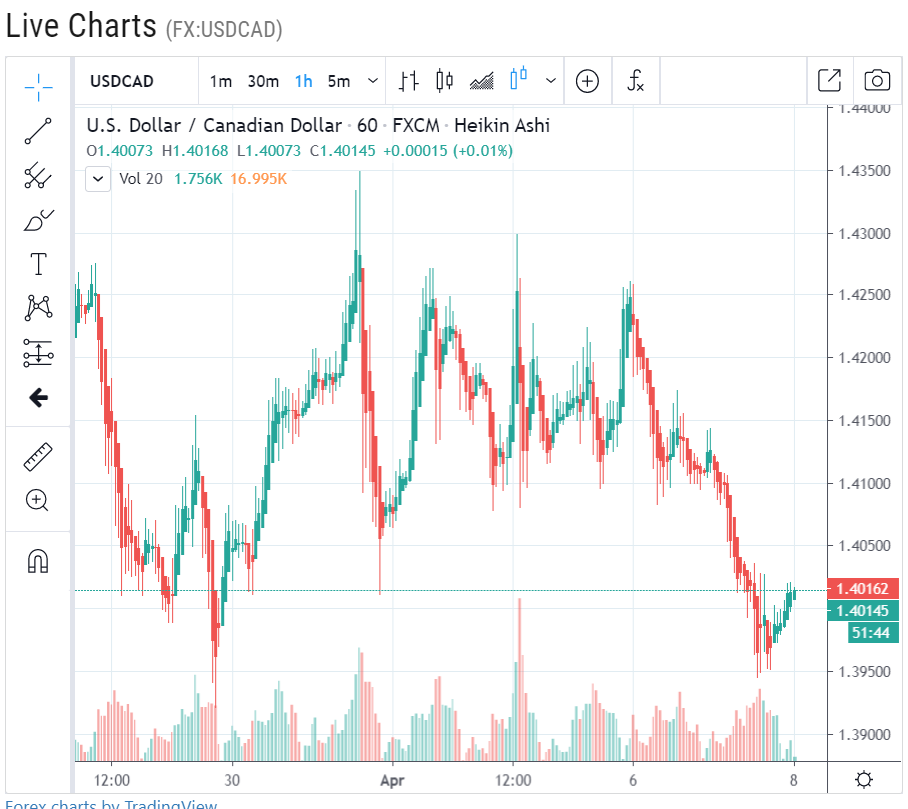
The US Dollar slid to an overnight and near 2-week low at 1.39454 before bouncing to finish at 1.3995 in late New York trade as Brent Crude Oil prices slipped 1.85%. In early Sydney trade USD/CAD rose further to 1.4017 as risk appetite waned and stocks reversed gains to close in the red.
Overnight Canadian data saw Ivey Purchasing Manager’s diffusion Index slump to 26.0 in March from February’s 54.1 and widely missing forecasts at 50.1 A level below 50 indicates economic contraction. Meanwhile, the latest Commitment of Traders/CFTC report saw net speculative Canadian Dollar shorts reverse and turn long from -CAD 29,245 to +CAD 7,316. That’s a huge turnaround. Lower Oil prices will continue to weigh on Canada’s economy and the Loonie will struggle to rally against the Greenback.
USD/CAD has immediate support at 1.3975 followed by 1.3945. Immediate resistance lies at 1.4020 followed by 1.4080 and 1.4130. Look to buy dips with a likely range today of 1.3990-1.4120.
AUD/USD – RBA Rhetoric, Risk-On Boost Battler, 0.6230/50 Caps
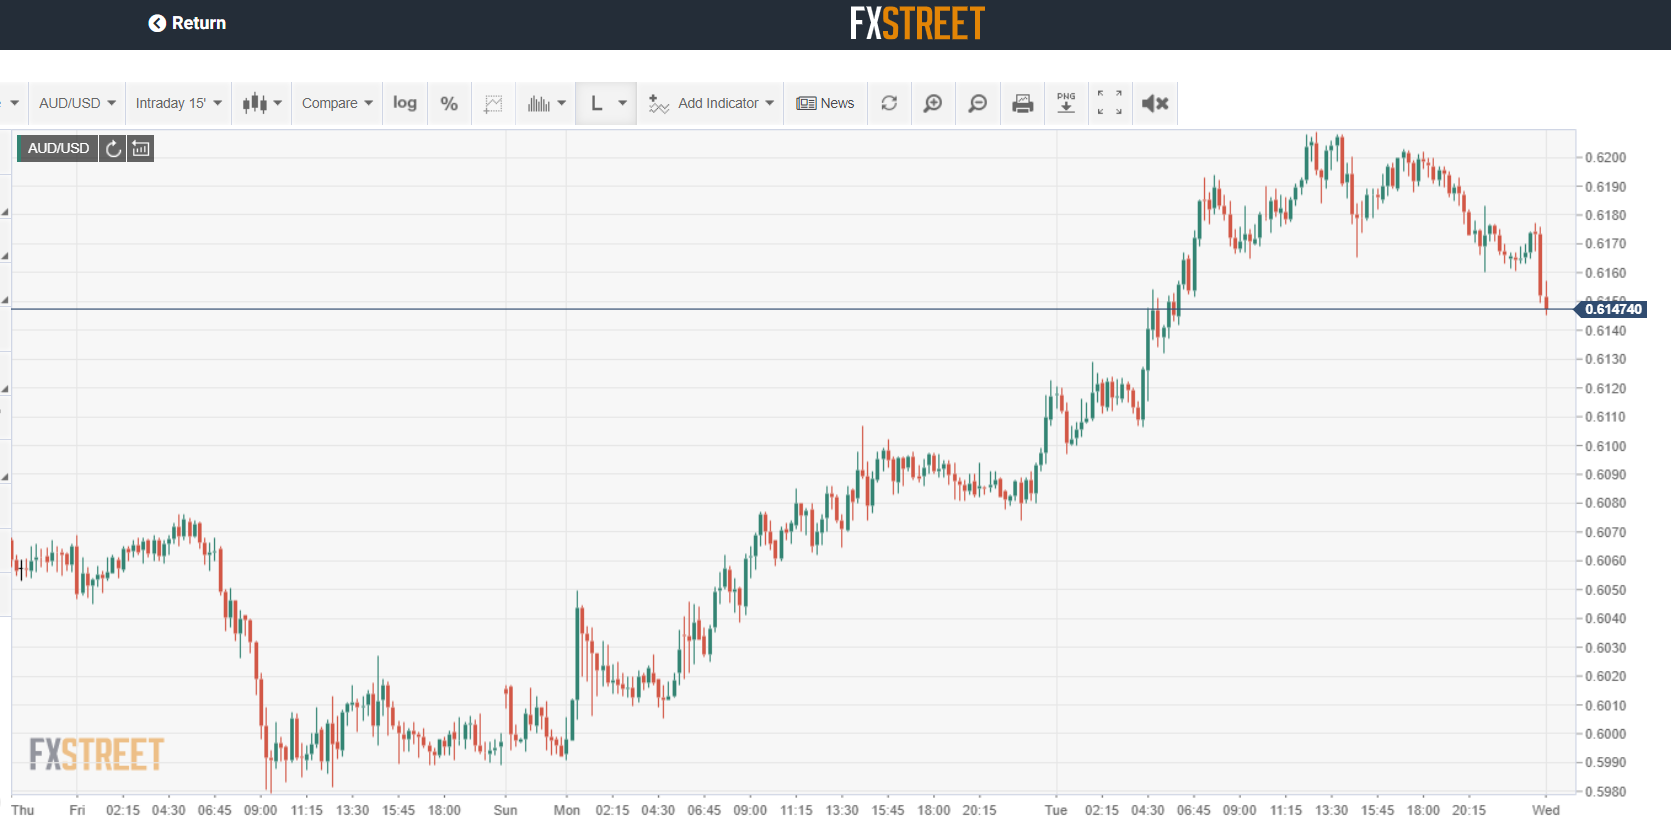
The Australian Dollar, battered to 2002 lows towards the end of March, bounced back strongly, only to hit a brick wall at the 0.6200/20 area. Yesterday the Aussie made another attempt to rally past 0.6200/20, jumping from 0.6100 only to be thwarted by willing sellers at 0.62080. The RBA kept its Official Cash Rate at the all-time low at 0.25% while maintaining policy and its current QE program. Rhetoric from the Australian central bank that they would continue to monitor financial conditions, and should conditions ease, its likely it would reduce the size and frequency of bond purchases. This saw Australian 10-year bond yields lift to 0.90%, up 13 basis points from 0.76%. With US 10-year bond rates at 0.71%, this puts Aussie yields ahead of the US.
The RBA is a bit premature to suggest they would taper QE at this stage. Tomorrow sees the release of the RBA’s Financial Stability review. Coronavirus headlines will continue to drive FX, including the Australian Dollar. So far Asian Covid-19 cases have been under the radar because there is not much reporting done and the focus is on Europe and the US. This could change soon and negatively affect the Aussie.
AUD/USD has immediate resistance at 0.6210/20 followed by 0.6250. Immediate support can be found at 0.6160 followed by 0.6120. Look for a likely range today of 0.6130-0.6230. Prefer to sell rallies, the Battler is not quite out of the woods just yet.
EUR/USD – Bounce Off 1.0780 Lows Will Struggle Through 1.0950
The Euro had a good bounce from its overnight lows at 1.07837, trading to a high at 1.09262 before easing to settle at 1.0895. Broad-based US Dollar weakness boosted the shared currency. The Euro’s strong bounce was also the result of optimism as the number of deaths dropped in Spain and Italy. The effects on the economies of both countries have yet to be seen.
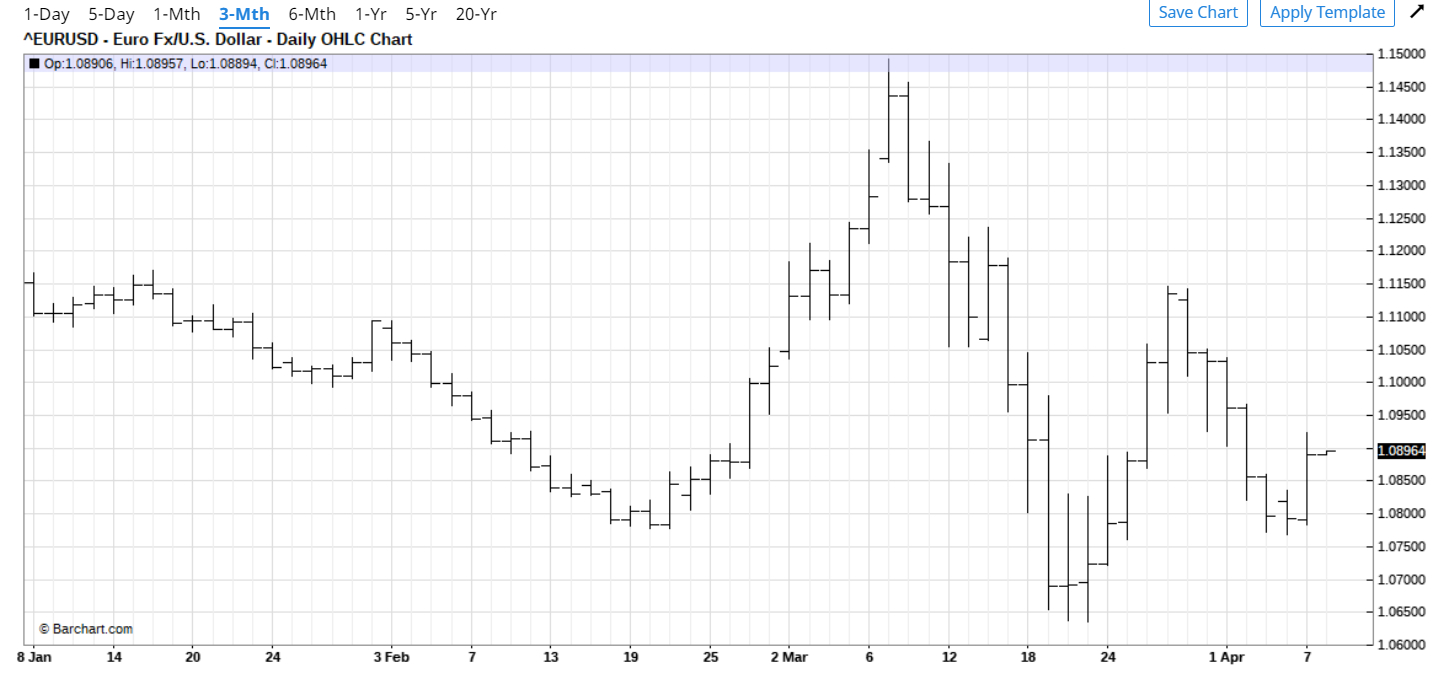
We reported that net speculative total Euro long bets increased to +EUR 74,247 bets from +EUR 61,290. These are the largest number of longs since June 2018. This will continue to reduce any strong upside potential in this currency pair.
EUR/USD has immediate resistance at 1.0930 and 1.0960 with 1.1000 as strong. Immediate support can be found at 1.0860 followed by 1.0820 and 1.0780. Look for a likely trade between 1.0840 and 1.0940 today. Prefer to sell rallies while the speculative market remains long.
Reporting by Michael Moran. Filed 8 April 2020, 01:42 GMT.


