HYCM: Is Big Tech Signaling the Worst is Over? (Not Yet)
The worst fears of equity bears appear to have been avoided by big tech firms this earnings season, with earnings beats from Microsoft, Alphabet, Meta, and Amazon.

by Giles Coghlan, Chief Market Analyst, consulting for HYCM
The worst fears of equity bears appear to have been avoided by big tech firms this earnings season, with earnings beats from Microsoft, Alphabet, Meta, and Amazon. A contingent of analysts had been forecasting that Q1 earnings would be the catalyst that finally sends stocks lower in 2023.
However, earnings figures from the above tech giants appear to be painting a slightly different picture. Earnings and revenue beats across the board and solid forward guidance has bolstered spirits on Wall Street just as this year’s equities rally was appearing to run out of steam.
Tech Earnings Better than Feared
In a higher interest rate environment that hammered tech valuations last year, the tech industry’s biggest names have weathered the storm, made cutbacks, and now find themselves in better shape heading into the second quarter.
Microsoft
Microsoft stock bounced more than 8% following an earnings surprise of $2.45 per share, beating expectations of $2.23 per share. Revenues also surprised to the upside, the company reporting $52.86 billion to analyst expectations of $51.02 billion.
Alphabet
Alphabet also beat analyst expectations on both top- and bottom-lines, announcing earnings-per-share of $1.17 to expectations of $1.08, and revenues of $69.7 billion, beating the market’s expectations of $68.96 billion.
Meta
Meta has been one of the tech darlings of this earnings season, its stock having gapped up by almost 15% after the company reported revenue growth for the first in three quarters in a row of declines.
The combination of positive earnings, cuts, better-than-expected forward guidance, and the announcement of a $70 billion stock buyback has the stock trading at its highest level since February of last year. Meta announced earnings-per-share of $2.20, beating analyst expectations of $2.03, on revenues of $28.65 billion, versus analyst expectations of $27.65 billion.
Amazon
Amazon shares also jumped on positive earnings. The e-commerce giant has seen its recent cost-cutting spree paying off, having reported better-than-expected earnings and revenues. Earnings came in at $0.31 per share to analyst expectations of $0.22 per share. Revenues were reported at $127.4 billion, beating Wall Steet’s expectations of $124.6 billion.
Common Themes
These four tech giants have collectively cut more than 50,000 jobs this year, making efficiency a big theme for the early part of 2023. This is perhaps the other side of the AI story, with many expecting the widespread use of AI to lead to further losses in white collar jobs. Meta CEO, Mark Zuckerberg, was explicit in his intentions to harness AI technology to increase engineering efficiency at the company.
As far as the Generative AI arms race goes, Microsoft’s acquisition of Chat GPT parent company, Open AI, currently places it at the front of the pack, at least in the public view, with Chat GPT having garnered the most attention due to its very public rollout this year. Google appears to be a few steps behind; its own Google Bard AI having been rushed to market with mixed reviews, and Meta’s own LLaMA framework, which is intended for AI researchers and not for public use, hasn’t really generated much of a buzz yet.
Another common AI-related theme across earnings calls was the slowing of the cloud computing market as customers cut costs in an uncertain economy.
The growth of Amazon’s AWS platform slowed to 16% in the first quarter, down from 20% in Q4 2022, having steadily declined in the past four quarters from 33% in Q3 of 2022.
The growth of Microsoft’s own Azure platform also slowed in Q1, down to 31%, from 38% in Q4 of last year, and 42% in Q3. The company expects it to drop further to 27% in the current quarter.
Alphabet’s Google Cloud platforms also saw growth slowing down to 28% in the first quarter, dropping from 32% in Q4 of 2022, down from 38% in Q3.
Despite the obvious trend, there was consensus across earning calls that companies would be increasing capital expenditure in their respective cloud infrastructures in anticipation of a surge in demand due to AI use cases.
Market Response
Recent earnings relief has had a marked effect on the broader market indices. Such is the outsized influence these big names exert on the overall market.
The S&P 500 bounced from the 4075 level, rallying to the top of a range the index has been trading in since the end of March. The last time the index reached these levels was at the beginning of the year, when it failed to break above 4180. This is the level the S&P is currently testing.
When we look at the Nasdaq, recent post-earnings trading has caused it to bounce off the bottom of its own recent range, between 12,900 and 13,200. The Nasdaq, however, has broken higher, reaching as high as 13,300 in recent trading, a level last seen in August of 2022.
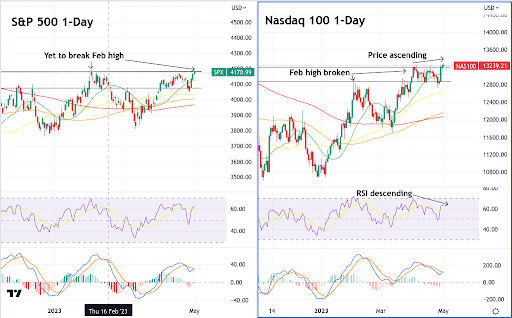
From a technical standpoint, the recent bout of buying hasn’t changed the fact that 2023’s rally appears to be running out of momentum. Both the S&P and the Nasdaq are currently setting daily lower-highs on their respective RSI’s.
Meanwhile, the S&P 500 has yet to break out of its own recent range to set a daily higher-high. The Nasdaq has, which is now leading an RSI divergence to form on the daily timeframe.
So, is the worst over? Both the Nasdaq and S&P have recently set weekly higher-highs, which brings August 2022’s high at 13,600 in sight for the Nasdaq and 4300 for the S&P. Nevertheless, it may still be too early to tell. And with on-going pressures in the banking system, and the prospects of higher-for-longer, there are still many headwinds to a change of trend.
The AI story, however, doesn’t show any signs of slowing down, and it will be interesting to see whether AI excitement is enough to galvanise the bulls, or whether the technology itself is sufficiently mature to start conferring measurable increases in productivity. These will be themes to follow in the coming quarters.
Trading Stocks
HYCM clients can trade stock CFDs on major names including Microsoft, Alphabet, Meta, Amazon, and more. In addition to that, as part of its on-going commitment to the equities investors, HYCM will be announcing a major addition to its existing stocks offering in the nearest time.
About: HYCM is the global brand name of HYCM Capital Markets (UK) Limited, HYCM (Europe) Ltd, HYCM Capital Markets (DIFC) Ltd, HYCM Ltd, and HYCM Limited, all individual entities under HYCM Capital Markets Group, a global corporation operating in Asia, Europe, and the Middle East.
High-Risk Investment Warning: Contracts for Difference (‘CFDs’) are complex financial products that are traded on margin. Trading CFDs carries a high degree of risk. It is possible to lose all your capital. These products may not be suitable for everyone and you should ensure that you understand the risks involved. Seek independent expert advice if necessary and speculate only with funds that you can afford to lose. Please think carefully whether such trading suits you, taking into consideration all the relevant circumstances as well as your personal resources. We do not recommend clients posting their entire account balance to meet margin requirements. Clients can minimise their level of exposure by requesting a change in leverage limit. For more information please refer to HYCM’s Risk Disclosure.
*Any opinions made in this material are personal to the author and do not reflect the opinion of HYCM. This material is considered a marketing communication and should not be construed as containing investment advice or an investment recommendation, or an offer of or solicitation for any transactions in financial instruments. Past performance is not a guarantee of or prediction of future performance. HYCM does not take into account your personal investment objectives or financial situation. HYCM makes no representation and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast, or other information supplied by an employee of HYCM, a third party, or otherwise.
Reporting by Giles Coghlan, Chief Market Analyst, HYCM. Filed 4 May 2023, 10:04 GMT.


