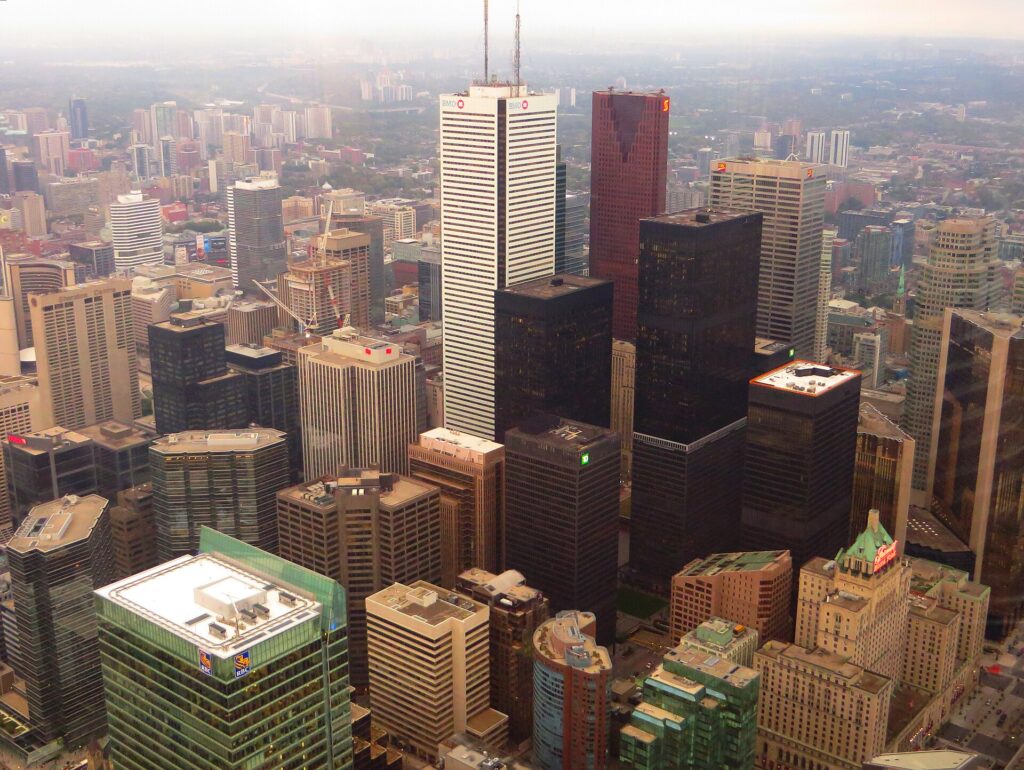
Canada’s six largest banks have agreed to jointly explore a Canadian-dollar tokenised deposit system, starting with transfers between the banks themselves. What the September 22 joint release does not name is more telling than what it does: no ledger, no operator, no launch date and, most importantly for an interbank-first design, no settlement asset. A token moving between banks remains a claim on the sender until something final settles the obligation, and the six have not said what that will be.
That gap matters because Canada has already tested one answer. In March, the Bank of Canada ran Project Samara with RBC and TD, settling a C$100 million Export Development Canada bond in wholesale central bank deposits on a Hyperledger Fabric platform. Whether the tokenised deposit rail copies that model or leaves obligations between commercial banks decides how much settlement risk it removes.
What the six banks announced
The participants are Bank of Montreal (BMO), Canadian Imperial Bank of Commerce (CIBC), National Bank of Canada, Royal Bank of Canada (RBC), The Bank of Nova Scotia (Scotiabank) and TD Bank Group. According to the release, “the first phase of the project aims to move tokenized deposits efficiently across Canadian financial institutions with a longer term goal to connect with other emerging digital assets initiatives.” The banks said they “anticipate the inclusion of other deposit-taking institutions at the appropriate time”, leaving credit unions and smaller lenders outside phase one.
The legal ground was cleared 12 days earlier. On September 10, the Office of the Superintendent of Financial Institutions (OSFI) issued a statement on tokenised deposits saying tokenised deposits “are, for example, not legally distinct from traditional deposits.” It also tells institutions to meet guidelines B-13 on technology risk and B-10 on third-party risk, and to engage their OSFI lead supervisors before launching any novel product. Each of the six therefore faces its own supervisory conversation over shared infrastructure.
Where the banks already stand
BMO, RBC, CIBC, TD and Scotiabank declined to comment further and National Bank did not respond, The Globe and Mail reported. Scotiabank and TD are among 21 banks backing a separate joint US-dollar stablecoin targeting the first half of 2027, and BMO went live this year as the first bank on CME Group’s tokenised cash platform on Google Cloud, according to Decrypt. National Bank backed a regulated digital Canadian dollar with Shopify in May, CoinDesk noted. Of those bets, the joint rail is the only one denominated in Canadian dollars and shared by all six.
“It’s an efficient way for the banks to settle amongst themselves,” Todd Roberts, senior partner of national payments and market infrastructure at Deloitte Canada, told The Globe and Mail. He argued that without a tokenised Canadian dollar, demand would drift to US-dollar digital assets. Eric Richmond, country director and CEO of Coinbase Canada, told CoinDesk the joint move is “a clear sign that more of the financial system is moving onchain.”
Why the timing collides with the Real-Time Rail
The announcement lands one quarter before Payments Canada’s Real-Time Rail (RTR) is due to go live in Q4 2026. Western University professor Cristián Bravo told The Globe and Mail that tokenised deposits could serve as an alternative to the RTR, which has faced repeated delays. For banks that have spent years funding RTR integration, a parallel always-on rail raises an obvious question: which system carries which flows, and who pays to run both.
The global comparison sharpens that. In the US, JPMorgan, Citi, Bank of America and Wells Fargo are building a tokenised deposit network through The Clearing House targeting the first half of 2027, per Decrypt. Swift’s ledger logged its second confirmed live transaction, a weekend payment between DBS and Citi on September 5, CoinDesk reported. As Partior’s instant payments have shown, a fast token leg does not by itself remove the settlement-bank leg underneath. Asia has moved from pilots to listed product, as the Hana Bank digital bond on SGX showed, and MAS is drafting powers over systemic stablecoins.
What to watch next
Three disclosures will separate plumbing from positioning. The first is the settlement asset: a Samara-style link to Bank of Canada wholesale money would make the tokenised deposit rail a genuine reduction in interbank credit exposure, while settlement between commercial banks would mostly move existing exposures onto a new ledger. The second is access: a six-bank venture with no named operator will be judged on whether “other deposit-taking institutions” join on equal terms. The third is sequencing against the RTR go-live. Until the banks name a ledger, a date and a settlement model, the project is a statement of intent backed by a regulator’s clarification, not a working rail.
This article is informational analysis only and is not financial, investment, or trading advice. Cryptocurrencies are highly volatile and can lose substantial value rapidly. Past performance and historical patterns do not guarantee future results. Do your own research and consult a regulated financial adviser before making any investment decision.
Karthik Subramanian
Karthik Subramanian is a founder, writer, and technology consultant with nine years in the crypto ecosystem. He covers token economics, L1/L2 infrastructure, DeFi protocols, wallets/custody, and the bridge between crypto and forex—broker technology, liquidity, and macro drivers. Karthik’s writing focuses on clear, practical frameworks that help professionals evaluate new products and on-chain innovation alongside FX market realities.
