Nubank’s Visa-veteran CFO starts amid US bank charter push
Rob Livingston takes over as Nubank CFO on July 13, 2026. Hiring a Visa finance chief — not a banker — signals how the US charter push will be monetised.
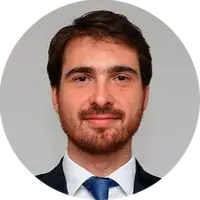

Rob Livingston takes over as global Chief Financial Officer of Nubank on July 13, 2026, and the most telling thing about the appointment is where he came from. Nubank did not hire a banker. It hired a card-network finance chief — Livingston spent 12 years at Visa, most recently as Chief Financial Officer of North America, after 18 years at Capital One (Nubank). For a company sitting on conditional approval from the Office of the Comptroller of the Currency (OCC) for a US national bank charter, that choice reads as a strategy statement: the American expansion is being built around payments economics, not deposit gathering.
It also lands in a quarter that has quietly reshuffled two of the most closely watched finance chairs in payments. While Nubank installs a Visa veteran, Adyen is losing Ethan Tandowsky, its Chief Financial Officer since 2023, who departs on August 31, 2026 for what the company described as an opportunity outside fintech — a pre-IPO company. Adyen’s supervisory board is still searching for a successor (CFO Dive). Two of the sector’s benchmark issuers are changing finance leadership within weeks of each other, and they are moving in opposite directions.
What Nubank is actually buying
Livingston replaces Guilherme Lago, who held the role for five years and moves to a special adviser position. He inherits a business with genuine scale: 135 million customers across Brazil, Mexico and Colombia, first-quarter 2026 net income up 41% year on year to $871 million, and quarterly revenues that passed $5 billion for the first time (Banking Dive).
“Rob Livingston is the right person to lead the team through what comes next,” said David Velez, Founder and Chief Executive Officer at Nubank (Businesswire).
What comes next is the United States, and that is where the Visa pedigree matters. A neobank entering the US market has two broad routes to unit economics: net interest margin on deposits, or interchange and payments monetisation. Livingston’s career sits almost entirely on the second road — Visa’s North American P&L is an interchange and network-fee business, and Capital One built its franchise on card economics. Hiring him signals which lever Nubank expects to pull first.
The charter is the enabler, not the strategy
Having tracked neobank charter applications through this cycle, the pattern is consistent: the charter is rarely the point. Klarna’s filing for a US bank charter was explicitly framed as a way to end its reliance on partner banks and reclaim the margin those partners were taking. A charter removes a middleman and a cost line; it does not by itself create a customer proposition.
Nubank’s conditional OCC approval does the same work. It lets the company hold deposits directly, price its own products, and stop renting balance-sheet capacity. But the 135 million customers it already has were won on a card-led, mobile-first proposition in Latin America — not on savings rates. The CFO hire suggests Nubank intends to export the model rather than reinvent it for American conditions.
Where rivals are pointing
The competitive read-across is worth naming. Klarna is pursuing a Utah industrial bank charter through the Federal Deposit Insurance Corporation (FDIC) route. Nuvei has been rebuilding its own executive bench — a Chief Operating Officer, Chief Financial Officer and Chief Product and Technology Officer — ahead of closing its Payoneer acquisition. Equifax, meanwhile, paid $750 million for Círculo de Crédito to deepen its Mexican credit-data footprint, the same market Nubank is scaling into.
That is three separate players spending real money to own infrastructure they previously rented or accessed through partners. The direction of travel across payments, credit data and neobanking is the same: vertical integration, funded by scale that finally justifies the fixed cost.
What to watch
The near-term test is whether Livingston converts the OCC’s conditional approval into an operating US bank, and on what timeline. Conditional approvals carry conditions — capital, compliance build, and governance commitments that a CFO owns. Expect the first two quarters of his tenure to be about the cost of standing that up rather than the revenue it unlocks.
The second test is Adyen’s. A supervisory board hunting for a CFO while the company defends its take-rate against exactly this kind of vertically integrating competition is not a comfortable position. If Adyen appoints from inside, it is signalling continuity; if it goes outside to a payments-network or banking background, it is conceding that the competitive frontier has moved. The Industry Spread will be watching which way that search lands — it will say more about the next 18 months of payments than any funding round this quarter.
Reporting by Rick Steves. Filed 13 July 2026, 06:50 GMT.
Senior Reporter, Regulation and Fintech
Rick Steves has seen business and economics through many lenses. He joined the financial services industry in 2009, and has been a financial journalist since 2011.


